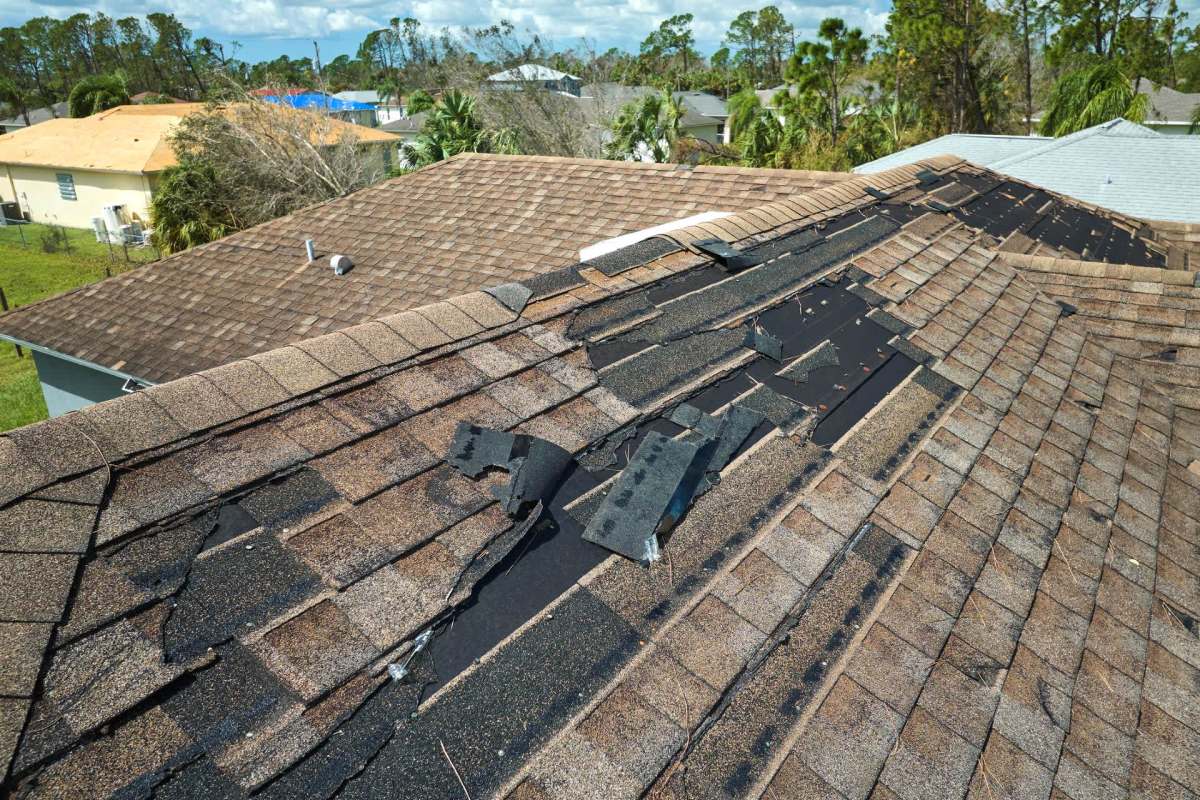
After an insurance adjuster approved a roof replacement for storm damage and issued a check, a homeowner faced another challenge: deciding how much information to share with prospective contractors. Looking for guidance, they turned to Reddit for advice.
Here's what to know
In a post on Reddit's r/homeowners forum, the homeowner asked how much insurance information they should share with contractors.
"This is my first time approaching the next step to setting up the work with contractors in this scenario," the original poster wrote. "I'm receiving advice to tell them it's a self-pay during estimates, to show them the insurance line items but hide the numbers, to just hand them the whole form.
"Any step-by-step advice on how to approach this?"
What commenters said
Commenters warned the OP not to share insurance information with roofing contractors, particularly when requesting estimates.
To ensure that the OP received estimates covering the same materials and scope of work, one user suggested asking two or three local roofers to inspect the roof and prepare their own descriptions of the work needed. The homeowner could then share the insurance adjuster's line items with the contractors afterward.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

One commenter, however, warned that accessing the insurance money could pose another obstacle for the OP if their mortgage servicer was named alongside the homeowner on the payout check. They advised checking the payees and, if both were listed, contacting the servicer's "loss draft" or insurance claims department for instructions.
For large claims, a servicer may release funds in stages after conducting inspections to ensure the work is being performed. The insurance company's paperwork requirements might also include the contractor's licensing and insurance information, a signed agreement, and a W-9.
Several commenters urged the homeowner to review whether the settlement paid actual cash value or replacement cost value and whether it included recoverable depreciation.
One commenter warned that missing a submission deadline for required paperwork could cost the homeowner. For example, some policies release withheld depreciation only after repairs have been finished and a final invoice has been submitted.
What can be done?
Commenters advised comparing estimates item by item, from permits and decking allowances to vents, drip edge, underlayment, and shingles. One commenter said contractors could price the work independently if they received the approved scope with the dollar amounts hidden. Others noted that roofers can use photos to support supplemental claims when an adjuster overlooks damage or code requirements.
When it came to choosing a contractor, commenters recommended asking friends or co-workers for references and picking established local businesses with fixed addresses. They also advised getting proof of insurance, warranties, and a start date in writing.
Commenters cautioned against offers to "cover your deductible," requests for large deposits, or pressure to sign immediately, as these could all be signs of unscrupulous businesses.
One commenter noted that keeping detailed records could help with depreciation payments, mortgage servicer requirements, and a future home sale. They recommended saving before-and-after photos, invoices, the contract, and the adjuster's report as well as checking whether a permit was required.
Where can I learn more?
Other homeowners have run into similar questions about roofing estimates, insurance claims, and paying contractors.
• A North Carolina roofer cashed a homeowner's insurance check, then filed for Chapter 11 bankruptcy.
• Roofers urged replacing a three-year-old roof after hail damage, but the homeowner feared another insurance claim.
• A California homeowner said a contractor wanted $3,000 more after receiving $13,400 through Zelle.
• A California homeowner received $20,000 to $25,000 roof quotes, then learned about potential surprise costs.
• In Sacramento, a drone inspection prompted a $3,300 repair quote for a roof without leaks.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.