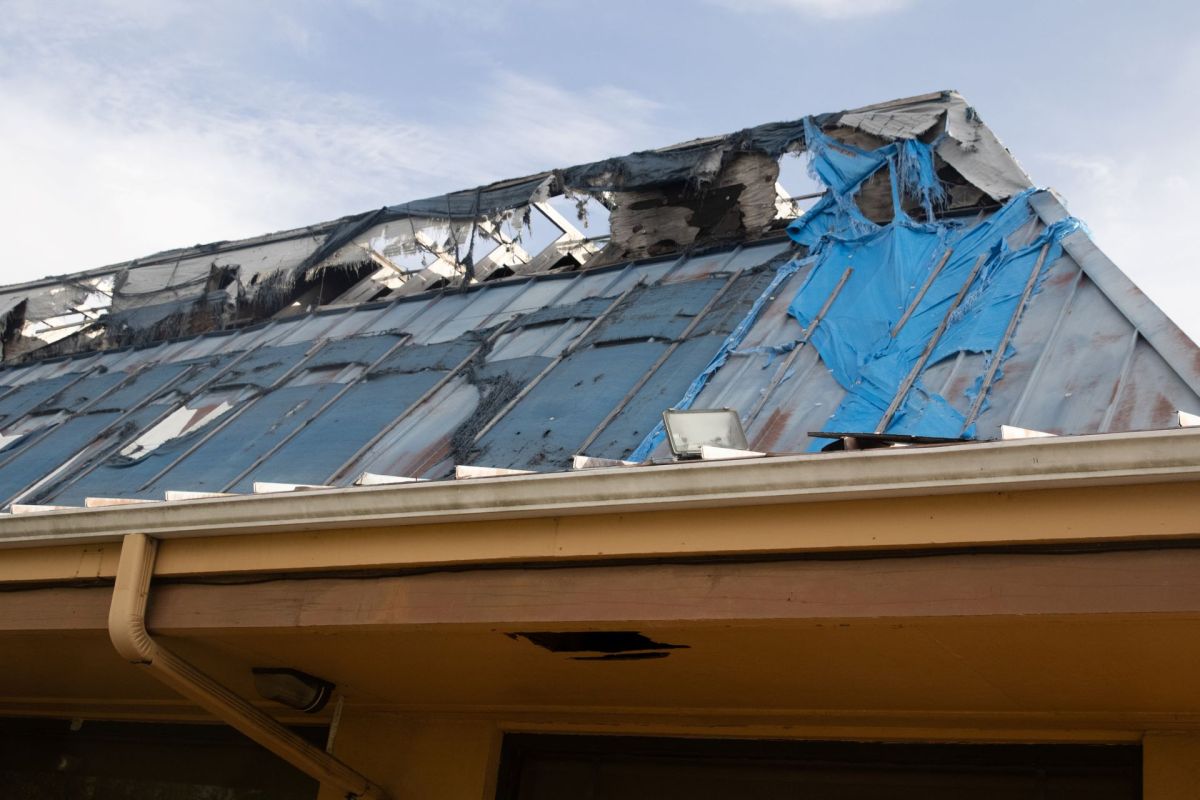
After a storm damaged a North Carolina homeowner's roof, a company took an insurance-funded deposit for a roughly $12,000 repair and then filed for Chapter 11 bankruptcy
Here's what to know
On Reddit, they said they had already "filed a claim 6 with the NC courts," but described the more urgent issue as any immediate damage to the home from another hurricane.
"We do not have the funds to replace the roof fully on our own if there's additional damage," the homeowner wrote.
One commenter said they deal with bankruptcy as part of their job, and they suggested the situation might not be as dire as feared.
"Chapter 11 is typically used to reorganize — in other words, stay in business," they noted.
Other replies were less encouraging about getting the money back. One commenter said the homeowner would likely be treated as "an unsecured creditor" and warned: "You'll need to wait until the bankruptcy proceedings are over to find out if you get anything. It's possible you get nothing."
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

More background
The homeowner said the roofer came by after a major storm and was chosen from companies advertising in the neighborhood because it seemed to have good reviews.
That would typically be a good strategy, as one commenter observed that companies that market aggressively after storms can be "there as a money grab."
Someone said money tied to unfinished work is the "first thing paid back" after bankruptcy, but other commenters disagreed, and one suggested customers should expect only a small portion back if the company still has assets once the bankruptcy case advances.
Commenters also differed on the insurance question. One said insurers "should cover you" and then seek repayment themselves, while another person thought that the insurance company would not pay the OP twice for repairs.
What can be done?
One reply directed the homeowner to North Carolina's Homeowners Recovery Fund, saying that if the roofer was a licensed contractor, that state process might offer a way to recover money.
The homeowner said they were still waiting to hear from the property manager about damage to the house following the second hurricane while also trying to determine whether any of the earlier payments could be recovered.
Where can I learn more?
Homeowners dealing with storm damage often end up stuck between insurers, contractors, and mounting repair costs.
• In Florida, FedNat customers faced turmoil after a major insurance company went belly-up.
• After tornado damage, a homeowner described a months-long nightmare with the insurer.
• In California, homeowners alleged major insurers offered protection that was little more than an illusion.
• In Florida, residents were left to fend for themselves after disputed inspections.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.