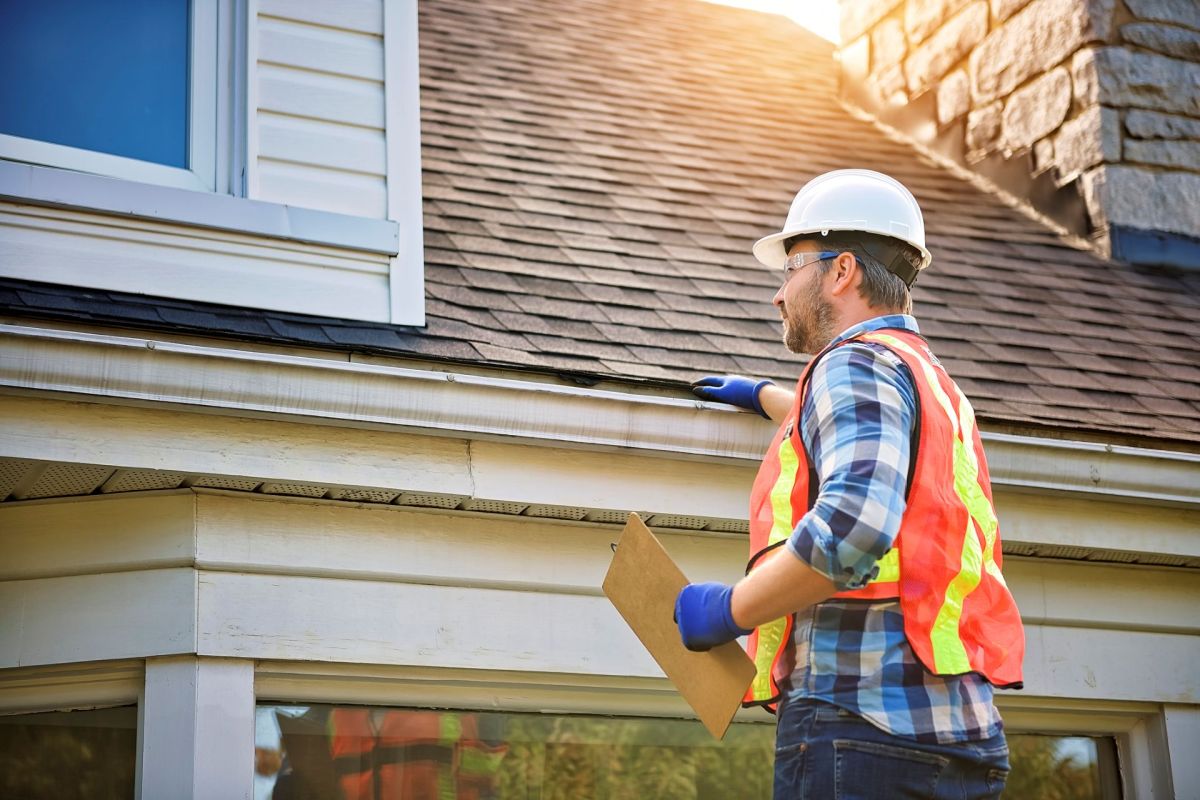
Shopping for home insurance can seem simple, until an aging roof turns a quick online quote into a much larger financial issue.
That was the situation one homebuyer described in a thread on Reddit's r/Insurance forum, after learning that one insurer might issue a policy, send an inspector, and then require a roof replacement.
Here's what to know
The concern centered on a home with a roof the buyer estimated to be somewhere between 15 and 30 years old. They wanted to know whether the prices they saw through online quote tools meant other insurers would actually accept the property as-is.
The original poster wrote: "Does that mean they will write the policy or is the older roof likely subject to inspection with them? … We've never dealt with this before. We've always just bought the insurance, but we've also never bought a house that is older like this one."
Commenters explained that the quoted premium online is different from a final approval after underwriting.
"All companies will do an inspection to confirm that it meets all their underwriting guidelines. If it doesn't, they will cancel the policy or advise you of what issues need to be addressed to keep the policy in force," the top comment explained.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

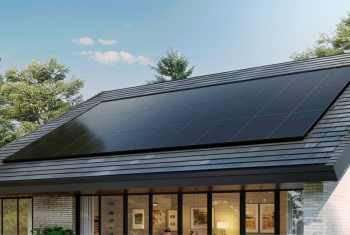
Insurers tend to become more cautious as roofs age because older roofs are more likely to leak or lead to expensive claims. In the thread, 20 years came up as a rough point when closer scrutiny often begins, even if the roof is not obviously failing.
So a buyer might receive a quote, complete an application, and even start coverage, only to learn after the inspection that the policy will stay in force only if the roof is repaired or fully replaced.
One commenter who said they work with inspections for Allstate offered a possible way to address the issue: "For roofs, having a contractor come out and write a letter that says no repair is needed (not estimated roof life remaining) can have the concerns cleared."
The commenter added that if repairs or replacement are necessary, completing that work can help secure coverage and may lower the premium.
More background
Because replacing a roof can cost thousands of dollars, learning that one may need to be replaced soon can put serious pressure on a buyer's budget and may even change whether the purchase still makes financial sense.
Roof age can also change the kind of protection a policy offers. Some insurers may still cover an older roof, but not on terms that would pay for a full brand-new replacement later, which could leave the homeowner covering much more of the cost after a covered loss.
Roof age is no longer a minor detail to check after an offer is accepted. It can shape insurance availability, monthly costs, and negotiating leverage before a sale is even final.
Where can I learn more?
Home insurance costs, policy terms, and nonrenewals are putting pressure on homeowners in a growing number of places.
• Homeowners are being hit by clauses buried in insurance policies that limit payouts after major losses.
• In Florida, insurance policy nonrenewals are increasingly pricing homeowners out of coverage altogether.
• In California, families could face coverage gaps after major insurer CSAA seeks another rate hike.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.