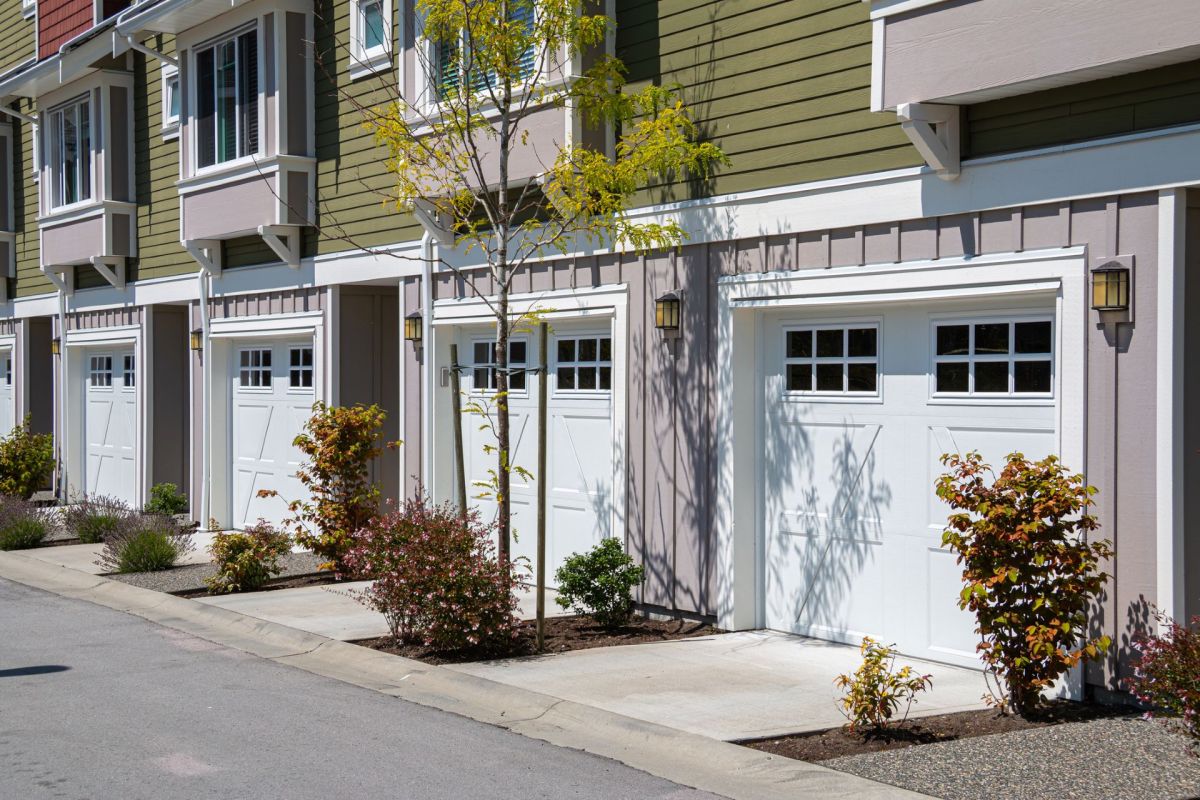
A California condo owner said tens of thousands in homeowners association assessments forced them to take out a loan, on top of the more than $1,000 they already pay in monthly HOA fees.
Here's what to know
In a Reddit discussion about buying in the Bay Area, one commenter described owning two condos in San Diego's Scripps Ranch area, including one they rent out. Each property carries a $514 monthly HOA fee.
In addition to those monthly payments, the owner said the association imposed a $22,000 special assessment on each condo, which they attributed to California's SB326.
"I had to take out a loan to cover that! ($44,000!)" they wrote.
The discussion began with a prospective buyer who said a detached house was financially out of reach.
"I live in the bay area so buying a house isn't really an option any time soon," the original poster wrote. "I like the idea of a townhouse anyways. What should I be cautious of? Also, if I wanted to rent bedrooms to people, is that typically allowed?"
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

More background
For condo and townhouse owners, upkeep of common areas, roofs, and shared walls is a collective financial responsibility. One commenter cited those obligations as a key difference from HOAs governing detached houses.
Reserves help associations prepare for major expenses, including roof replacement.
A low monthly fee can mean inadequate reserves, leaving owners to cover costs through special assessments, commenters explained.
The San Diego owner's account does not establish how often buyers should expect those charges.
Beyond maintenance bills, HOA rules can also prevent residents from making money-saving home improvements. Associations can restrict rooftop solar panels and native plant lawns. That's another reason to be wary if the fees seem unreasonable. For restrictions on home improvements, working with HOAs is often doable.
What can be done?
For a property under serious consideration, a Los Angeles condo owner suggested reviewing several documents, including the reserve analysis, at least a year's worth of meeting records, the financial plan, and the association's governance paperwork.
Evidence of proper management matters alongside the money in reserve, another commenter advised. They recommended measuring those funds against the association's reserve study.
Commenters directed the prospective buyer to the association's operating policies and its covenants, conditions, and restrictions, or CC&Rs, to determine whether the planned bedroom rental would be allowed.
The consensus was that the original poster needed to do some homework before deciding.
"There is no one-size-fits-all answer to most questions asked here," a commenter wrote. "The answers are in the governing documents and other records of each association."
As for the poster who had to take out a loan, some posters had less sympathy for their major payment, likening it to the expenses of owning a home and contrasting it with an apartment.
"The reason he had to pay $22k is that the balcony was dangerous and needed to be repaired," one wrote. "The law requires inspections on balconies and repairs made to bring it up to code. What a thing to be resentful for."
Where can I learn more?
Large special assessments have strained other condo owners' budgets, too.
• California condo owners face a $49,000 special assessment for a $24.4 million repair plan.
• San Clemente condo owners are challenging a $26,000 assessment that could force residents to move.
• Condo residents face five new special assessments after years of low HOA dues.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.