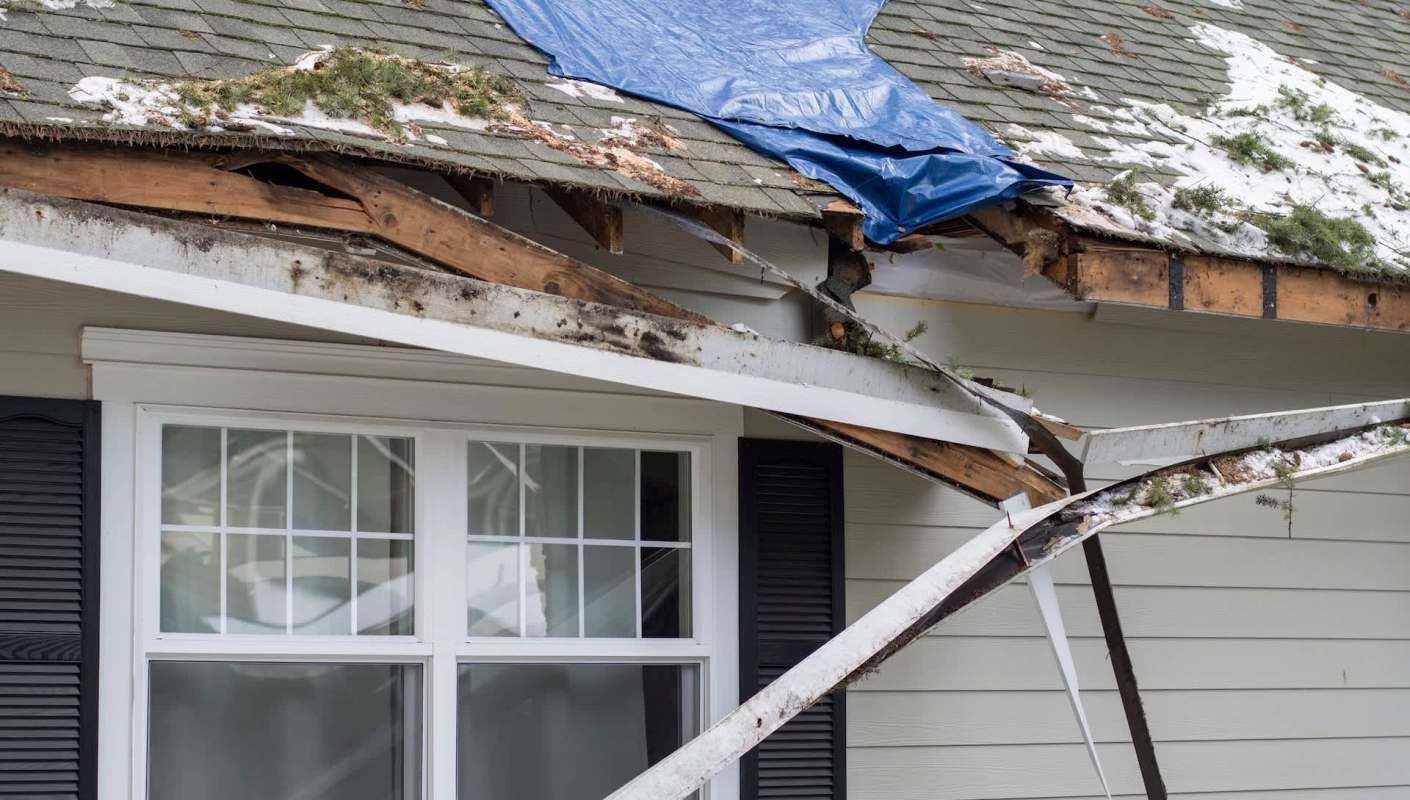
The United Kingdom's hottest summer on record helped drive 13,000 new home subsidence insurance claims in just three months, underscoring the costly consequences of prolonged hot, dry weather.
With average payouts for that damage holding at a record £20,000 ($27,000), the financial toll on insurers and affected communities is mounting.
Here's what to know
Insurers paid out £1.5 billion ($2 billion) across home and business claims between July and September 2026, according to Insurance Business, citing the Association of British Insurers' Property Insurance Tracker.
The outlet reported a 1% increase in total payouts alongside a 4% decline in claim volumes to 142,000, pointing to the growing expense of each claim. The average claim reached a record £10,000 (~$13,000) as repair costs increased.
"These record costs show the severe damage that extreme weather is now causing for communities and the need to boost resilience," commented Chris Bose, director of general insurance and international policy at the ABI, per Insurance Business.
Subsidence occurs when the ground beneath a property sinks. The publication reported that ABI members logged 13,000 new household subsidence claims during the quarter, versus 8,000 in the corresponding period of 2025. That was the highest quarterly total recorded.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

According to Insurance Business, the Met Office's provisional assessment ranked summer 2026 as the UK's hottest. The extended stretch of hot, dry weather made ground movement considerably more likely, while average home subsidence payouts remained at their record level for a second consecutive quarter.
More background
Domestic flood claims averaged £28,000 ($38,000), slightly below previous periods. Insurance Business reported that domestic fire claims averaged £38,000 ($51,000), ranking third among quarterly figures on record.
For households, these costs come alongside annual insurance premiums averaging £329 ($443). That figure was unchanged from the third quarter of 2025, though it had increased by £4 (around $5) from the second quarter of 2026.
Repair bills may exceed a property's insurance coverage when the amount insured still reflects older material and labor prices.
What can be done?
A coverage review with a broker is one step residential and commercial property clients can take in response to the rise in subsidence claims.
Insurance Business advised using the time needed to resolve claims as a check on whether business interruption and alternative accommodation limits are sufficient.
"It's vital that new homes are built to withstand increasingly frequent extreme weather and that we work together to improve the long-term resilience of our homes and businesses," Bose concluded, according to the outlet.
Where can I learn more?
The rise in subsidence claims shows how hot, dry weather can turn into costly property damage.
• U.K. and European insurance insiders say climate risk projections get a 'haircut'.
• The U.K. recorded a 28.1C September day, while drought recovery could take months.
• U.K. insurers caught fewer bogus claims, but fraud they blocked still totaled £1.34 billion ($1.8 billion).
• Britain's record heatwaves could bring a pothole surge for drivers, the RAC warns.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.