

Starting Social Security can change the math of retirement fast, but some of the biggest drains on a fixed income are older bills that never got revisited.
As MoneyLion detailed, a winning approach is to review a small group of familiar bills carefully, instead of cutting expenses without a plan.
Here's what to know
Smaller repeat charges deserve attention because they can grow into a meaningful drain over time. The financial experts at MoneyLion explored six bills to reconsider when retirement begins: Medicare and healthcare plans, auto insurance, life insurance, subscription services, membership fees, and housing and utility bills.
For healthcare-related plans, premiums and prescription coverage can change over time. The same is true for auto when coverage is based on a previous commute for work.
For life insurance, the math can change when children leave the house and no longer need support, while unused subscription services can sneakily deplete bank accounts. The same is true for memberships to bulk stores when buying in bulk for a large group is no longer practical.
But for retirees living on monthly checks, utility costs are arguably one of the biggest pressure points. One way to get them in check is to research senior discount programs, which are available in most states, retirement expert James Morgan told MoneyLion. The founder of FinanceCompassPro.com noted, "[They] usually require a phone call or application."
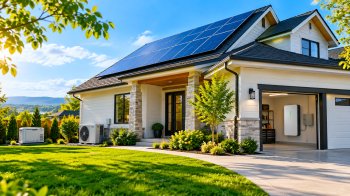
Going solar is also one of the best ways to save money on home energy, and homeowners can use EasyHome's free explorer tool to see pricing and savings from vetted installers in their area.
More background
Once retirement begins, daily routines can change quickly.
Crushed by your bills? See instant solar savings from vetted installers in just a few clicks With energy prices through the roof, there's never been a better time to go solar — and EasyHome can help you find the best prices from the best installers in your area. EasyHome takes the guesswork and headaches out of energy upgrades by showing you estimated savings from a network of vetted local partners. To get started, just enter your ZIP and share a few details about your home — seeing your estimate is really that easy. |
Driving is a prime example. Some households may decide they no longer need a second vehicle, and their annual mileage may drop enough to qualify for low-mileage or retired-driver discounts. Meanwhile, life-insurance coverage purchased to replace wages or help pay off a mortgage may no longer be necessary once those obligations have changed.
Still, attorney Greg DuPont, a certified financial planner, told MoneyLion that not all expenses should be treated as obvious cuts, particularly health insurance, home maintenance, and long-term planning. "Deferring any of these can lead to a much larger bill later," he said.
What can be done?
Instead of treating this as a one-time cleanup, Morgan recommended handling it as a yearly review. DuPont added that life insurance should be evaluated on more than just the monthly premium before a retiree decides to cancel it.
Beneficiaries, debts, final expenses, estate-planning goals, cash value, and possible tax or surrender consequences can all affect whether the coverage still belongs in the budget.
Housing can also offer savings opportunities that many retirees miss. DuPont told MoneyLion that most states offer senior property tax relief, but "it's routinely unclaimed because nobody applies." The experts also pointed to free movie downloads or DVD rentals through libraries, along with senior entertainment discounts that can stand in for some paid subscriptions
For homeowners looking at bigger energy savings, EasyHome's free explorer tool is a great resource to compare vetted installers and understand potential savings before making a decision. EasyHome can also help you explore battery storage options. Pairing solar with a battery can maximize solar savings and keep the power on when the grid goes down.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.