

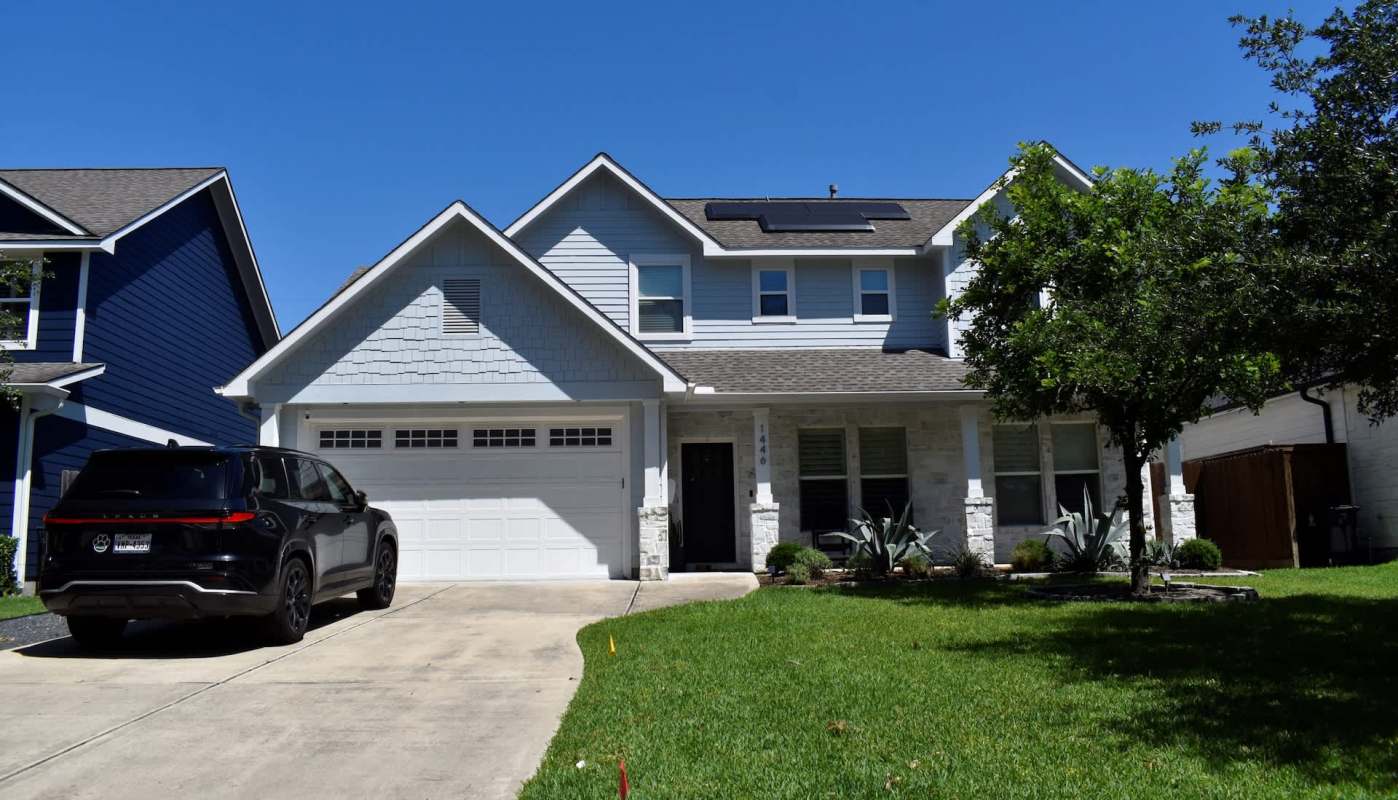
For a 66-year-old homeowner facing declining health, paying off a $32,000 mortgage could offer some relief on the path to retirement. But with only $135,000 in savings, doing so would require nearly a quarter of their retirement account. Looking for outside opinions, they turned to Reddit.
Here's what to know
In Reddit's r/personalfinance community, the original poster asked whether withdrawing retirement savings to pay off the remaining mortgage balance makes financial sense. On their current payment schedule, they would pay off their mortgage in 2030.
On the one hand, the $32,000 withdrawal would leave just $103,000 in the OP's retirement account before any potential taxes. On the other hand, paying off the mortgage would immediately reduce their monthly payment obligations.
More background
Several commenters noted that for a long-term mortgage so close to its payoff date, principal likely accounted for relatively little of each payment. However, because the OP did not provide the loan term or interest rate, commenters could not know for certain.
"If you were on a 30 year with just a few to go, it's likely all principal. So unless monthly payment causes cash flow issues, I would not pay off the mortgage," wrote one user. "Especially if you get a tax hit by pulling the money out to pay down the mortgage."
Other alternatives
Commenters proposed several other alternatives, including downsizing to a less expensive home. One user offered the example of selling a $200,000 house and purchasing another for $100,000. However, such a switch would require additional expenses, such as transaction costs.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

While offering general opinions, many commenters admitted that more precise recommendations would require a clearer picture of the homeowner's budget, retirement plan, and mortgage terms.
"It would be super helpful If you provided your annual expenses, your expected Social Security benefit, and your current interest rate and home payment (mortgage versus taxes and insurance.)," wrote one. "It often does not make financial sense to pay off your home loan early if that means drawn down limited retirement funds."
Where can I learn more?
For homeowners nearing or already in retirement, weighing how much of their savings to tie up in housing is a common concern. These stories explore mortgage payoff decisions, downsizing, equity release, and the financial pressures older homeowners face.
• A 73-year-old with $200,000 saved weighed paying off a mortgage against keeping cash available.
• A homeowner nearing retirement said that keeping a beloved house would account for 65% of expenses.
• A U.K. mother nearing 60 considered accessing her home equity, while commenters warned about depleted assets.
• Only 28% of U.S. homeowners 55 and older expected their finances to improve as costs continued to rise.
• A retiree considered selling a paid-off home to rent rather than buy somewhere smaller.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.