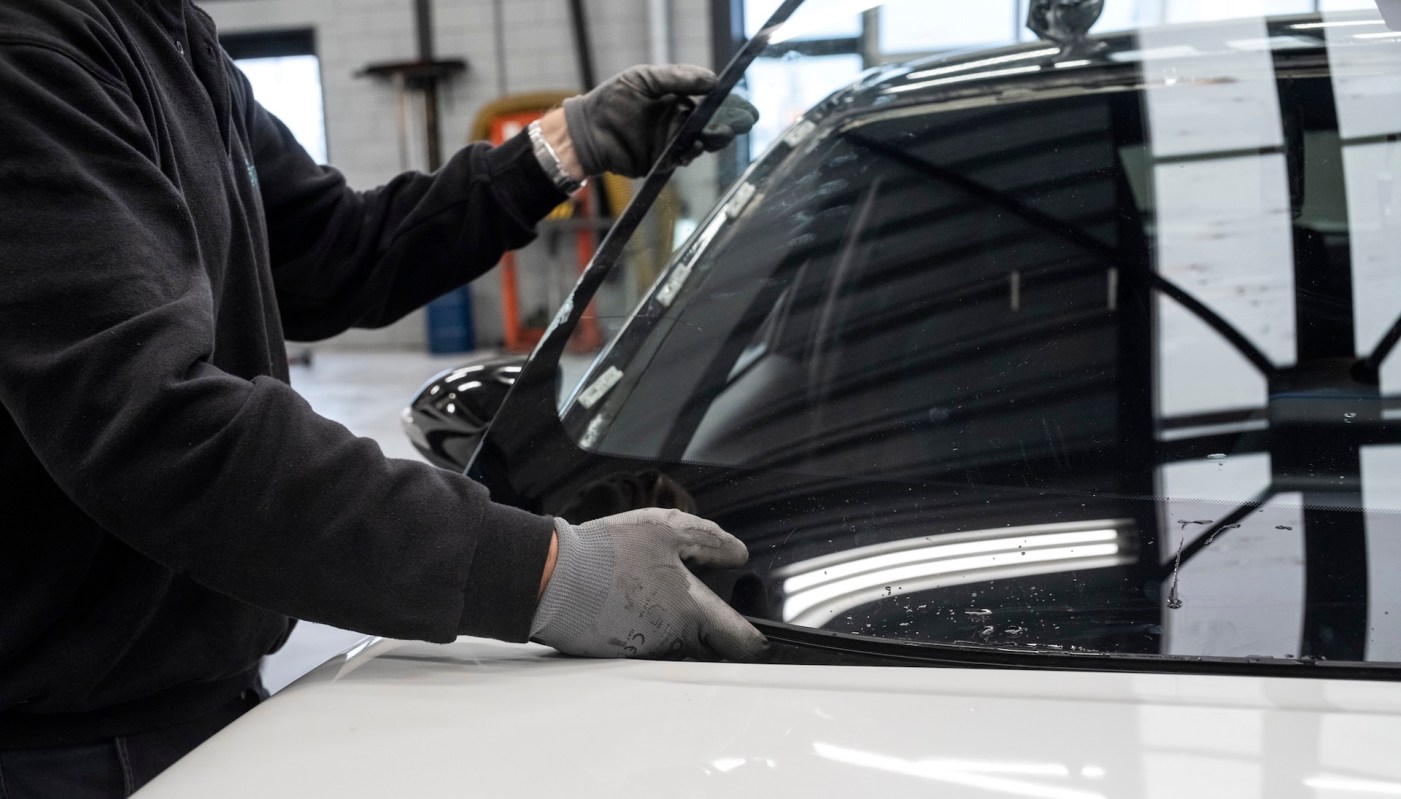
A $416 windshield quote put one Ohio driver in quite a pickle.
They were torn between using their $0 comprehensive deductible to potentially cover the full cost or holding off and paying out of pocket to protect against a future premium or rate increase.
Here's what to know
The Ohio State Farm policyholder raised that issue in a Reddit thread. Because of their deductible, the glass replacement might be fully covered. As they explained to the r/Insurance subreddit, they were unsure whether filing the claim could have future consequences.
The numbers were straightforward, as one auto-glass company quoted the driver $416 for a new windshield. Before deciding, they also planned to check a few local glass shops for lower cash prices while weighing whether it made more sense to use the policy or pay out of pocket.
Most commenters leaned toward paying cash. Not because the deductible would block coverage, but because they believed a small claim could reduce a discount or hurt future pricing.
"Call your agent as you may lose a claim free discount that could cost you the same over the next three years," one warned.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

Several Redditors also focused on the repair itself. One commenter urged the driver to consider local options, saying, "You'll get better service, faster, at a better price and using better glass if you search for local shops and read their Google reviews to find the best one."
Another suggested they "call around to other shops," after finding a national option more expensive when they replaced their windshield.
More background
The bigger issue for the driver was the possible long-term impact of submitting a glass claim under comprehensive coverage. They wanted to know whether that kind of claim could stay on the record in a way that affects later premiums, including if they switch insurers.
One commenter said they had "two replaced for no increase in later rates," while another said they had done "3 or 4 glass claims" for chip repairs without seeing a premium increase.
Others argued that the answer depends heavily on both the policy language and the state involved.
"This is dependent on state and carrier… some states it's a comp claim which will raise rates, some states are deductible less glass claims, some carriers are first windshield in policy term," one explained.
What can be done?
Checking prices with independent glass shops was one of the clearest practical suggestions in the discussion.
Commenters also suggested contacting the insurer or agent before opening a claim. That could help clarify whether glass is treated as a standard comprehensive claim, whether any claim-free discount could disappear, and how the policy handles windshield replacements.
One commenter got to the bottom of the OP's dilemma, saying they didn't see a "wrong choice."
"If it's not a hardship then pay it out of pocket," they advised. "Comp claims shouldn't affect your rates too much, but they can add up if you wind up getting a ticket or into an accident. On the flip side, you pay for a $0 deductible, use it."
Where can I learn more?
A small claim can feel more complicated when insurance prices are already shifting in so many places.
• Across the U.S., climate impacts are pushing car insurance rates higher faster than drivers expect.
• In the Netherlands, one insurer stopped covering fat-tire e-bikes as theft and losses mounted.
• In North Carolina, homeowners were told to expect a massive insurance rate spike soon.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.