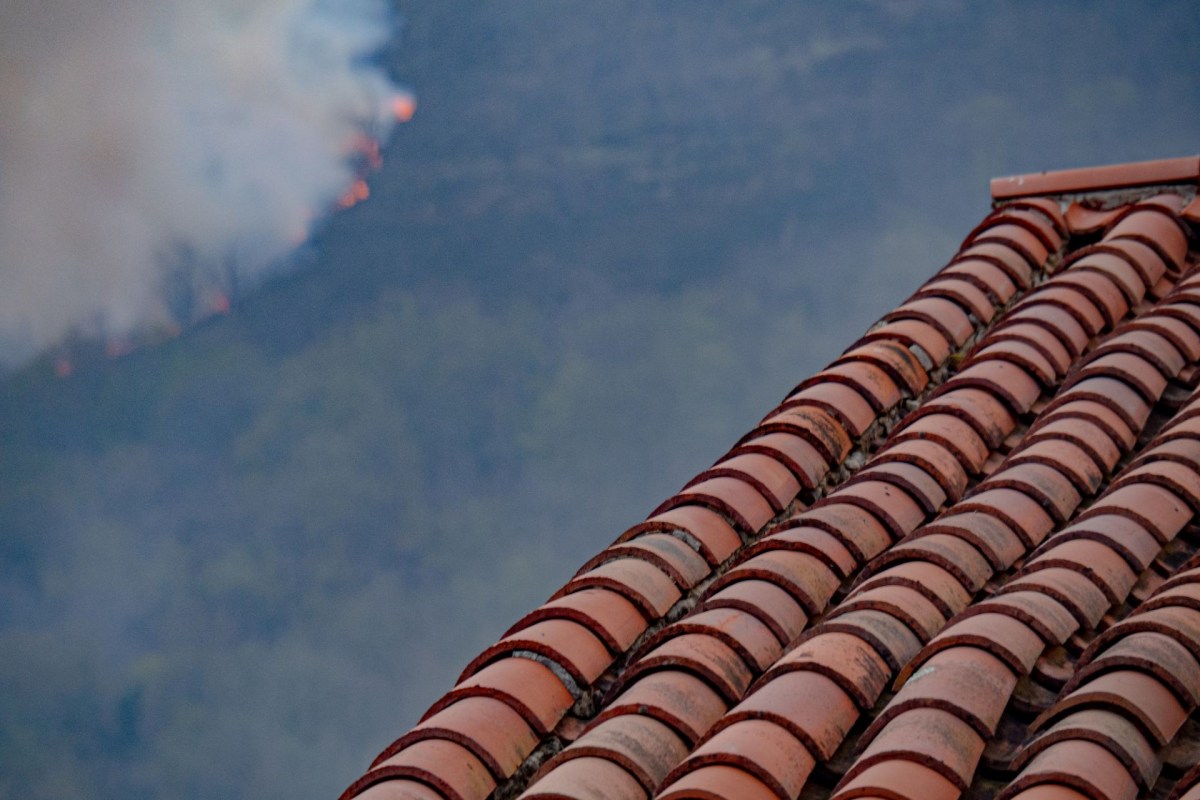
Buying a brand-new home in Southern California should be one of the easier parts of settling down.
In the Inland Empire, though, buyers are finding that even newly constructed houses in suburbs considered lower risk can be hard to insure completely, deepening the strain of an already costly market.
Here's what to know
According to a new Los Angeles Times analysis, the state's insurance crunch has spread beyond mountain towns and canyon areas long associated with wildfire danger. The effects are increasingly visible in fast-growing inland communities where much new housing has gone up.
Near Menifee, tech worker Alex Hwang said that when he was buying a six-bedroom Pulte house for about $700,000 in June 2026, the policy he could secure from Summit Specialty came with a $25,000 fire deductible before coverage would kick in.
"I hate the $25,000, but I didn't really have a whole lot of choice," Hwang said. "None of the big-name insurance companies were writing."
From March 2025 to late June 2026, the Times found that 9 out of 10 new FAIR Plan policies in 396 ZIP Codes were classified as low-risk. FAIR Plan counts in stretches of the Interstate 215 corridor climbed by about 300% to 500%.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

Speaking to the state Assembly in June 2026, Insurance Commissioner Ricardo Lara said, "We are finally seeing the signs of stabilization in our insurance market."
Even so, many home shoppers still have fewer standard-market choices.
More background
The issue goes beyond price alone. It also affects what coverage buyers can actually get.
As traditional insurers step back, homeowners often choose between two less-than-ideal paths: pairing a fire-only FAIR Plan policy with separate coverage for other losses, or buying a surplus lines policy outside the regular market.
Weiss Ratings data shows how fast that segment has expanded: surplus lines companies accounted for 1% of California's home insurance market in 2021 and 7% in 2026.
Another buyer, Louis, a Riverside County resident, said he struggled to secure insurance for a roughly $700,000 house in Promontory near Murrieta.
"We were panicking," he said.
In the end, they bought a surplus lines policy from Indiana-based Orion180 with a $14,000 deductible for fire damage.
"People always talk about how unaffordable California is as a state …. so here's another thing to tack onto that," Louis said. "Can you afford a home? Great. Can you afford the insurance?"
What can be done?
California's insurance department has responded unevenly to the rise of surplus lines carriers.
Michael Soller, a spokesman for Lara, said that Lara's focus is on expanding access to comprehensive coverage rather than "skinny policies that promise savings but don't deliver full protection."
"Insurance used to be the last thing that everybody did when they bought a house: 'Oh, I gotta get insurance. OK, give me like three days,'" Riverside insurance broker Bob Severns said. "And now? Now it's the first thing."
Where can I learn more?
These articles cover dropped coverage, steep rate hikes, and California's response.
• Across California, homeowners faced 400% insurance rate hikes as carriers pulled back coverage.
• California officials took unprecedented action on coverage after major insurers stopped renewing homeowners.
• In California, coverage for new homeowners tightened after a major insurer halted policies.
• A new California rule forces insurers to write more policies in wildfire areas.
• Before the Palisades Fire, Los Angeles residents were failed by their insurers during evacuations.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.