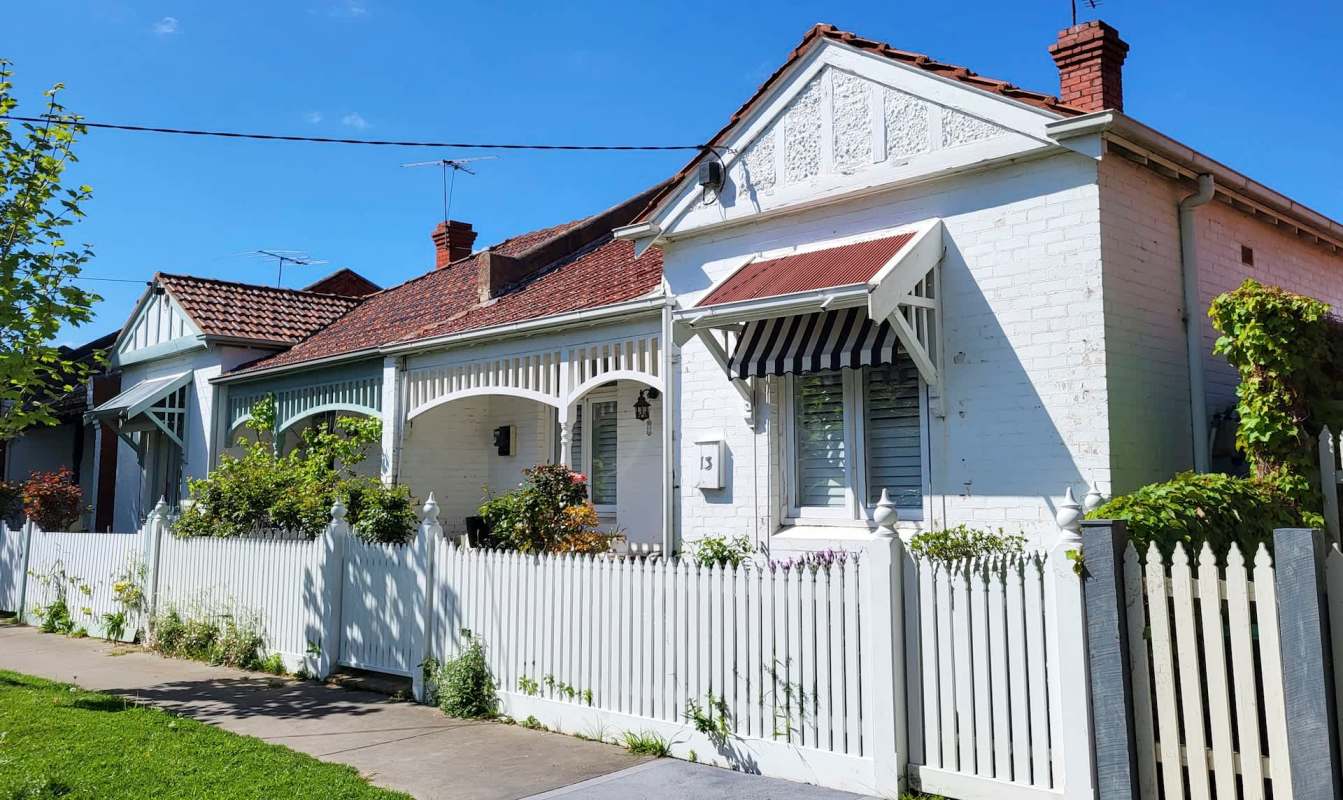
Across Australia, homeowners are receiving renewal notices with home insurance costs hundreds or even thousands of dollars higher, yet with no clear reason for the jump.
New research suggests the problem is widespread: three in four renewal notices reportedly offer no explanation for premium hikes, leaving households to either absorb the cost or risk going without coverage, CHOICE reported.
Here's what to know
CHOICE, which partnered with the Financial Rights Legal Centre, reviewed 52 home insurance renewal notices and found that none gave a clear reason for the higher premium.
In 75% of the notices, there was no explanation. In the remaining 25%, the explanation was generic rather than specific to the property.
The General Insurance Code of Practice says renewal notices should explain any premium increase and place the previous premium alongside the new one.
CHOICE found that 9.6% of renewals omitted the prior year's premium, 92% did not include it on the first page, and 19.6% did not present both figures together on one page.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

Julia Davis, principal of external relations and advocacy at the Financial Rights Legal Centre, said consumers get little useful information about why their costs are rising.
"Insurers know more about the risks facing our homes than anyone else, yet consumers are routinely given a premium increase without any meaningful explanation of what's driving it," Davis observed.
Morgan Campbell, CHOICE's head of policy, noted that it is unsurprising that public trust is weakening in that environment.
"Homeowners are clearly frustrated with skyrocketing premium increases that arrive without clear justification," Campbell added.
More background
CHOICE reported that the reviewed renewal notices showed an average increase of 16%.
Still, many rose by 25% to 50%, and some reached 100%.
In a separate survey of 831 home insurance policyholders, CHOICE found that 71% said they did not know why the price had risen, while 73% felt the increase was unfair.
One homeowner, identified as Michelle, said her Apia premiums increased 42% over two years despite an absence of submitted claims and no obvious change in risk.
"There is nothing to justify the increase," she explained. "No claims, no flood zone, no robberies in the area, and the property is well protected. It is now more expensive to insure my home than my health."
Another homeowner, identified as Rachel, saw her AAMI premium rise from $6,132 ($4,261) to $8,576 ($5,959), while other major insurers would not cover her address at all.
When she requested a new quote from AAMI using the same details as her renewal, it came back about $500 ($347) cheaper.
"I feel I am trapped by this insurer, and that they can charge me whatever they want, knowing that no one else will insure me," Rachel lamented.
Home insurance premiums are now more than 50% higher on average than they were five years ago.
At the same time, APRA has estimated that climate-related affordability pressures could leave one in four homes uninsured by 2050.
What can be done?
Rachel's experience showed that asking for a fresh quote from the same insurer, checking that the coverage details are identical, and testing different excess or contents settings can reveal major pricing differences.
CHOICE and the Financial Rights Legal Centre are calling for changes to insurance law that would require insurers to explain the factors behind a premium increase and tell customers what actions could help reduce it.
The proposed changes would apply in areas facing elevated flood, fire, or storm risk, where homeowners are often encouraged to pay for resilience upgrades without being shown whether those investments will lower premiums.
"Instead of incentivising consumers to make their homes more resilient to climate change, cheaper premiums are often only offered to new customers, or if you threaten to switch," Campbell stated.
"We are not calling for exhaustive explanations, rather the provision of enough information for a consumer to understand the factors that led to the price they are paying," Davis said.
Where can I learn more?
Homeowners elsewhere are dealing with similar renewal shocks and coverage disputes. These stories cover steep premium increases, non-renewals, and policy terms that can leave households exposed.
• In Calgary, residents called policy renewal decisions "ridiculous" after insurers targeted northeast homeowners.
• Across North Carolina, steep insurance rate increases raised costs for homeowners statewide.
• Homeowners found that clauses buried in policies can drive up premiums and deductibles.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.