

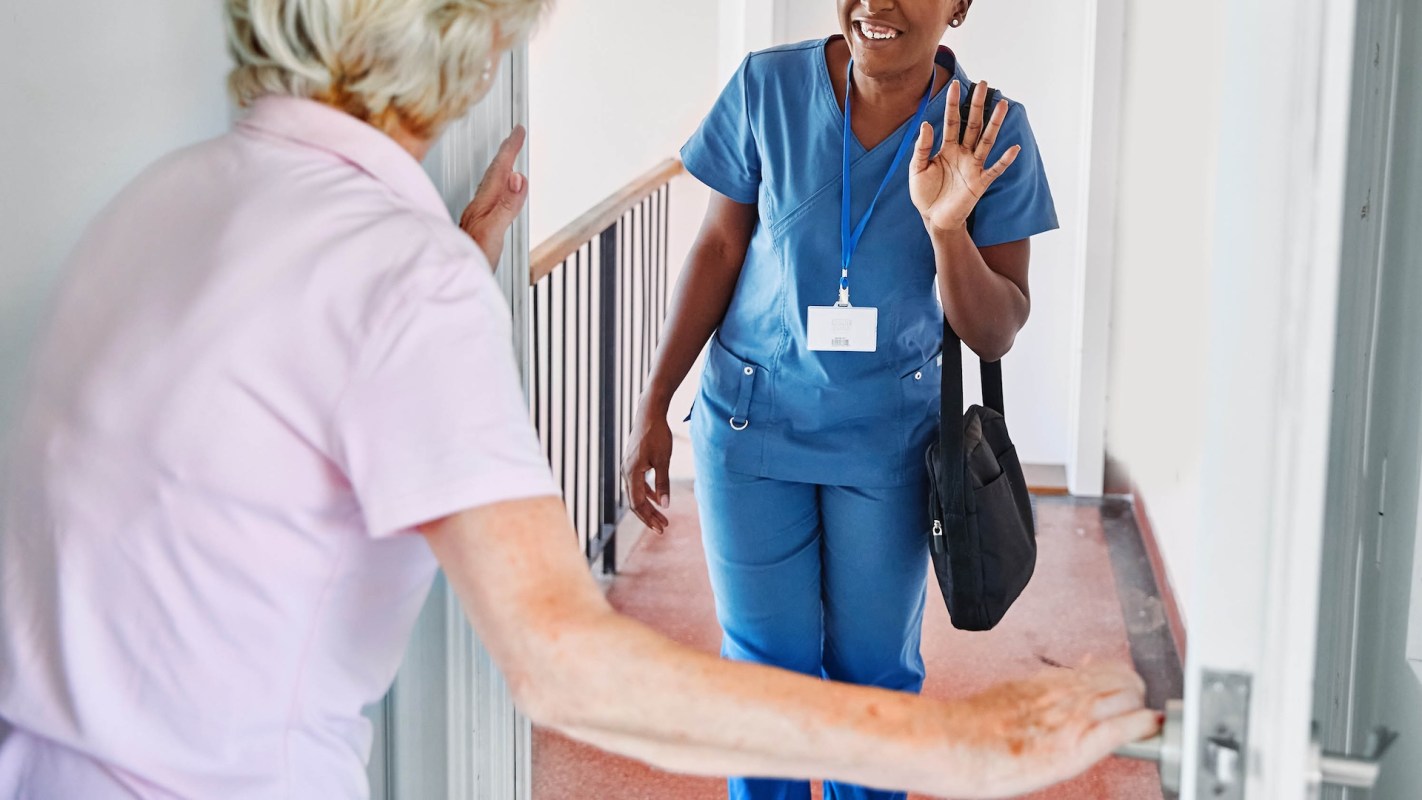
In Southwest Florida, staying in your home in old age can cost far more than many families expect, with private-duty in-home care running up to $45 an hour.
Money is only part of the problem; even households that can pay can struggle to find dependable caregivers and uninterrupted coverage.
Here's what to know
According to U.S. Bureau of Labor Statistics Consumer Price Index figures cited by WINK News, home care prices in the United States rose 7.9% between May 2025 and May 2026. Families in Southwest Florida told the outlet that rising costs, staffing shortages, and insurance confusion can quickly turn aging at home into a financial and logistical crisis.
The issue became immediate for Charlie Horning when his wife, Sandy Horning, had a stroke on Oct. 11, 2025, WINK reported. After about 100 days of rehabilitation, she came back home, and the family first arranged 24-hour care before later cutting that down to seven hours a day.
Based on Horning's experience, private-duty care cost about $35 to $45 an hour. "Medicare pays nothing, so you can't depend on that," he said, per WINK. "If you don't have long-term care insurance, it's out-of-pocket money."
Wendy Rickenbach, owner of Hometown Senior Care Solutions and a nationally certified dementia trainer, said 14 different caregivers came through the Hornings' home.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

"Very, very, very inconsistent caregivers," she said, per WINK. "It was like this family was having to manage all these people coming in and out of their home nonstop."
More background
Rickenbach said a major source of confusion is that families often don't understand the difference between Medicare-covered home health and the daily help many older adults actually need.
Rickenbach said services such as physical therapy, occupational therapy, speech therapy, and nursing are part of Medicare-covered home health, but, she added, "Medical insurance is medical insurance, not activity of daily living insurance," according to WINK.
Because the Hornings' long-term care insurance policy had a daily maximum, the family had to pay for any hours beyond that limit themselves. Rickenbach estimated that even a four-hour daily minimum costs about $4,560 per month, while families needing eight, 12, or 24 hours of care can face much higher bills.
Rickenbach said the field has only roughly one-fifth of the caregivers needed for the aging population and that in-home care costs have climbed about 15%.
She also said agencies can favor cases with longer paid schedules, making it harder for families seeking shorter shifts to secure consistent coverage.
Assisted living ultimately became the better-value option for the Hornings, though Horning said it was a painful choice after 52 years of marriage. He said it offered more socialization, more activities, and better value than continuing with inconsistent in-home care.
What can be done?
WINK said families should plan ahead so a medical emergency doesn't force rushed decisions.
Rickenbach recommended approaching elder care planning like retirement planning: Discuss what support may be needed, what it may cost, and how long savings could last at four, eight, or 12 hours a day.
Experts also urged families to read insurance policies closely. WINK noted that Yenisset Valentin, co-owner of WellTrust Health Group, said some people assume coverage will expand as care needs increase, but "sometimes a patient needs more hours because they're ill or because they need more service, and they don't offer that."
Researching providers early can also help. Jorge Valentin said the process is "extremely difficult," WINK reported. He said matching a caregiver to a patient involves vetting, interviews, and a meeting between both people to see whether the fit is right.
WellTrust focuses on companion services such as light housekeeping, errands, food preparation, medication reminders, and transportation to appointments or the grocery store.
Families can also ask financial advisers, long-term care insurance providers, hospice social workers, and the VA about available support. They should also ask agencies a practical question from the start: What happens if a caregiver calls out sick or quits?
For families trying to stay ahead of the issue, Rickenbach said, "At age 75, you really need to start focusing on how you're going to age and not where you're going to age."

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.