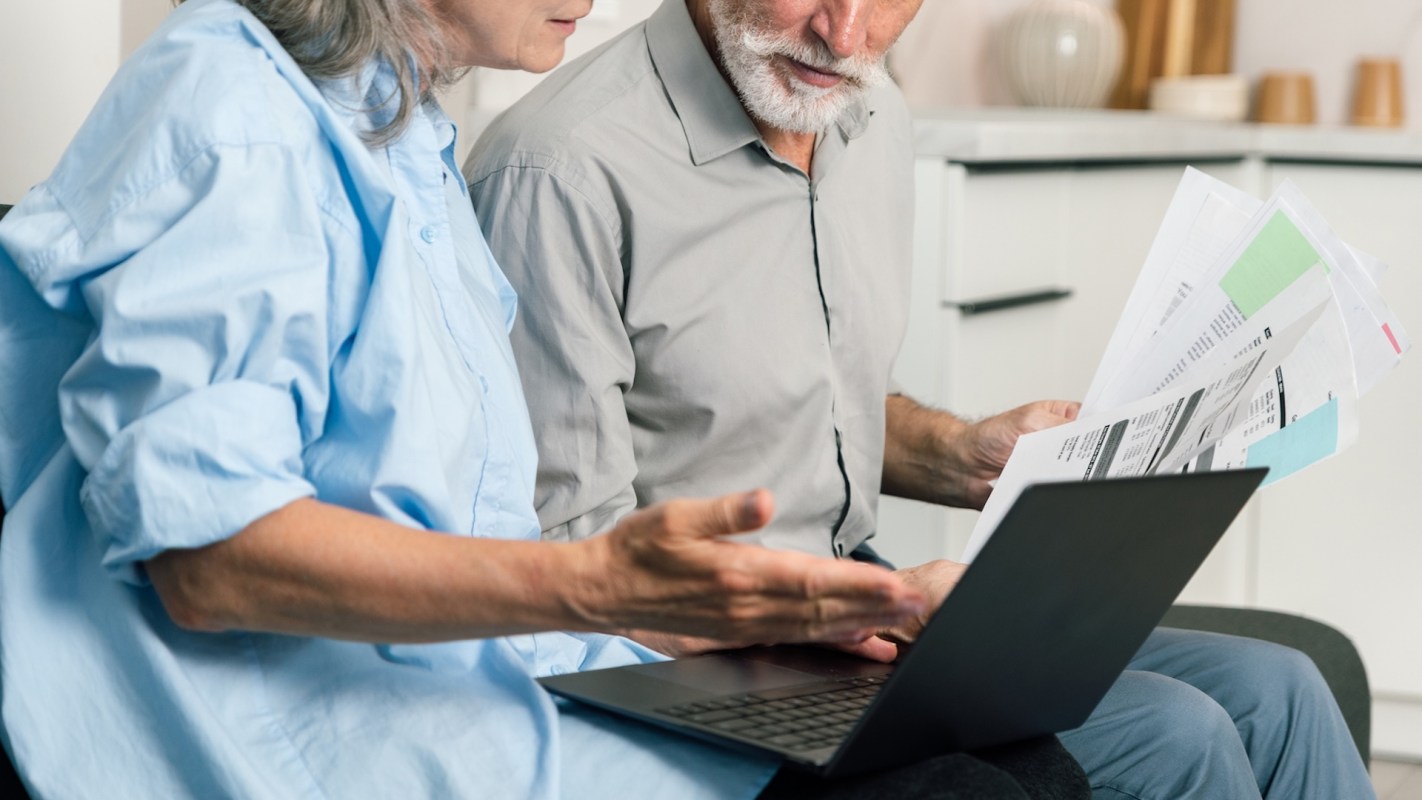
Federal retirees in one online forum are grappling with an increasingly difficult question: When Federal Employees Health Benefits premiums climb into five figures, is it still worth staying put?
For some families looking ahead to 2027, Blue Cross Blue Shield coverage alone could exceed $10,000 per year.
Here's what to know
The conversation began in a Reddit thread on r/FedRetirees where the OP laid out the projected cost of staying with Blue Cross Blue Shield: "With the latest increase, for 2027 it will be $10k+ a year for BCBS Basic for a family. BCBS Standard is close to $13K." They then asked the question driving the discussion: "Is going ACA and managing income carefully to max out subsidies the better play now?"
One retiree responded with their own numbers. They said they currently insure themselves and their husband through BCBS Standard for $890 a month, but plan to remove him from the policy when he turns 65 so he can use Medicare Part B and Tricare. "It will still cost me 420 a month."
Others said FEHB still compares favorably with what they could buy elsewhere.
One user said, "Self plus one for us in the 400s a month is impossible to beat," adding that private insurance would cost "many, many times that."
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

More background
Retirees are also weighing provider networks, deductibles, Medicare coordination, and the income-based surcharge known as IRMAA, which can raise Medicare Part B costs for higher earners.
For some, avoiding IRMAA is a major reason to keep FEHB.
One user called that "a very underrated benefit" and said that, once pensions, investment income, and IRA withdrawals are counted, their Part B premiums could be "something like $1,100/month."
Another user said, "This is the way, and no IRMAA."
Serious health scares also shaped the conversation.
One retiree said, "My husband almost died 2 years ago with extended hospitalization and rehab. We have standard BCBS and Medicare B. We paid nothing."
What can be done?
A lower-cost option mentioned in the thread was changing enrollment type.
One user advised, "If you don't have young children, you can move down to self or self+1." That shift alone can lower premiums compared with family coverage.
Users appeared more inclined to switch plans within FEHB than leave the system entirely.
The OP said, "Probably going to BCBS Focus or GEHA Standard is the safer play. It's less than half the cost of BCBS Standard."
Another retiree said they were leaving MHBP for GEHA because MHBP premiums looked too steep.
The ACA option came up mainly as a strategy for retirees who can tightly control taxable income. The OP said that premiums "can end up $0 on ACA" if adjusted gross income stays low enough for subsidies, but warned that "the plan may be crap with a narrow network and high deductibles, so really varies a lot by state."
Travel concerns surfaced too. One user warned that Medicare Advantage FEHB options may not pay for care on cruises because ships are treated as foreign.
They added, "If you go with a MA plan and cruise or travel internationally, consider travel insurance."
Where can I learn more?
Federal retirees aren't the only ones feeling squeezed by insurance costs. These stories look at rising home insurance premiums and climate-driven insurer losses.
• In Oklahoma, homeowners are paying 194% more for coverage than the national average.
• State Farm sought a 30% rate increase, intensifying pressure on already strained homeowners.
• Insurers are absorbing skyrocketing climate-related losses, a trend keeping premiums elevated.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.