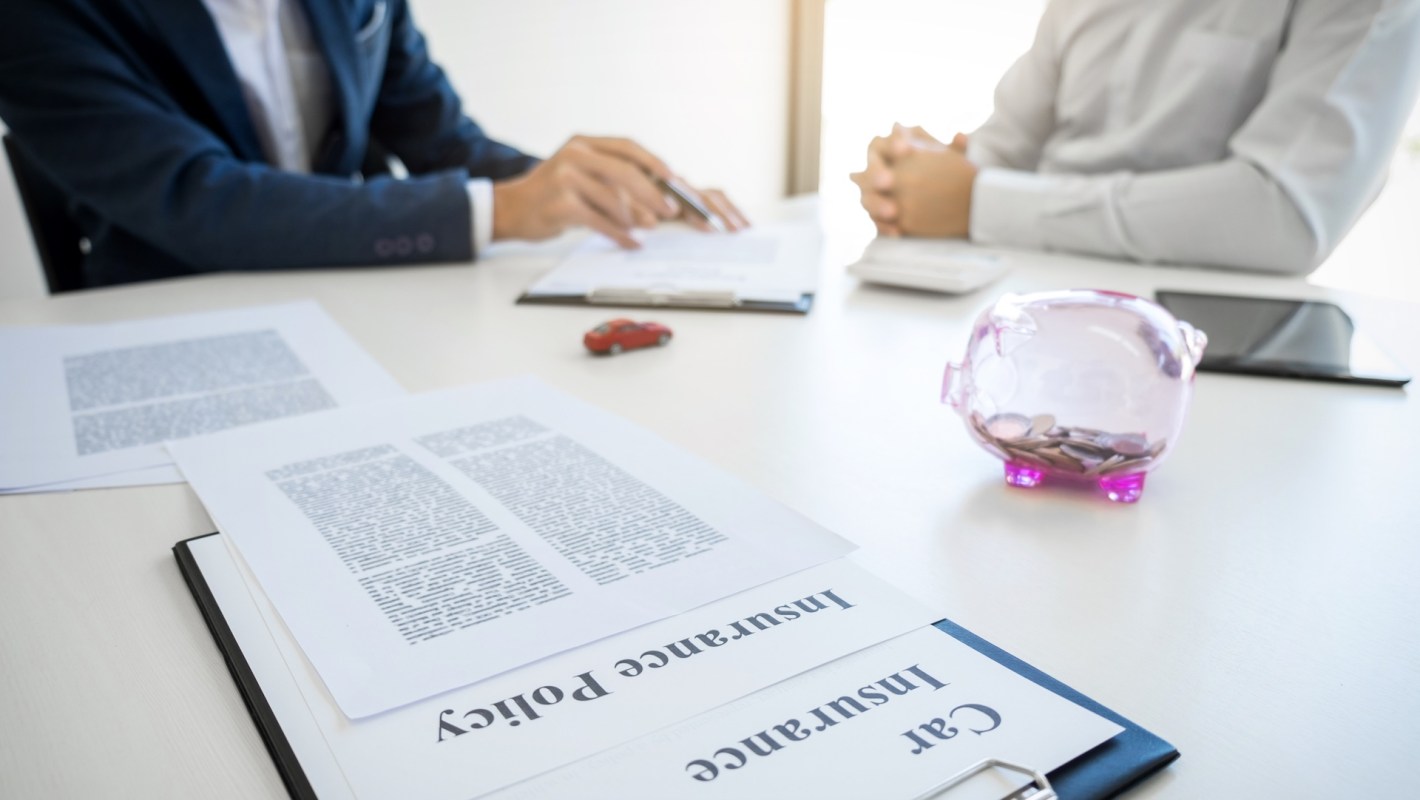
Replacing an aging truck could bring a costly surprise for one couple, whose quoted monthly auto insurance bill would rise from about $180 to as much as $405 after three years under a rate lock.
Here's what to know
The household's Erie Insurance coverage included a 2013 truck and a 2023 car. In a post on Reddit's r/Insurance community, the poster said they and their wife had been customers since 2023, with home and auto coverage bundled together.
The broker quoted a monthly auto premium of $335 to $405 to replace the truck. The poster had asked about used midsize and full-size models from 2017 through 2024, but the estimates represented a substantial increase over the couple's existing bill.
That would add approximately $1,860 to $2,700 to their annual bill, on top of the cost of buying the vehicle.
"We are both over 25, married, with no address changes, claims, or tickets. I apologize for my ignorance, as we don't jump around insurance companies a lot; is this normal? Would it be smart to get coverage elsewhere on the new vehicle?" the poster wrote.
More background
Replacing the truck could end the couple's protection from updated pricing, several commenters explained. They pointed to the rate lock as the reason years of increases hadn't previously hit the household's bill.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

Changes involving the garaging address, insured vehicles, or drivers could prompt a rate adjustment, according to one commenter.
A multivehicle discount was another possible factor, one commenter suggested. The couple had asked for a quote covering only the car, not the truck; under that arrangement, its monthly premium would rise to $168.51 from $97.23.
Another commenter explained that increases can accumulate while a customer's rate remains locked, becoming apparent only when a qualifying change triggers new pricing.
What can be done?
Erie remained the least expensive insurer in the broker's comparison, according to the poster. While comparing rates, the broker also identified possible savings. It would require the couple to remove the rate lock, but it could reduce the annual premium by $1,000.
Several commenters suggested asking about Erie Secure Auto, describing it as coverage without a rate lock. One commenter who mentioned clients in Illinois benefited from the program cautioned that it might not be offered in the poster's state yet.
One commenter said trying a different agency might produce a better price. Another recommended obtaining the broker's actual competing quotes. Both suggestions were among the calls to shop around again for the bundled coverage.
Where can I learn more?
Other drivers have seen their auto insurance bills jump or found ways to save by revisiting their coverage. These stories cover rising premiums in Colorado, increases for EV customers, and savings from requoting and bundling.
• Colorado's full-coverage rates jumped 36% as one Denver driver's bill reached $200 monthly.
• An EV owner saw insurance rise to $1,690 from $1,180, prompting debate over battery age.
• One driver said adding $10-a-month renters insurance cut their car premium by $25 monthly.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.
Cool Picks