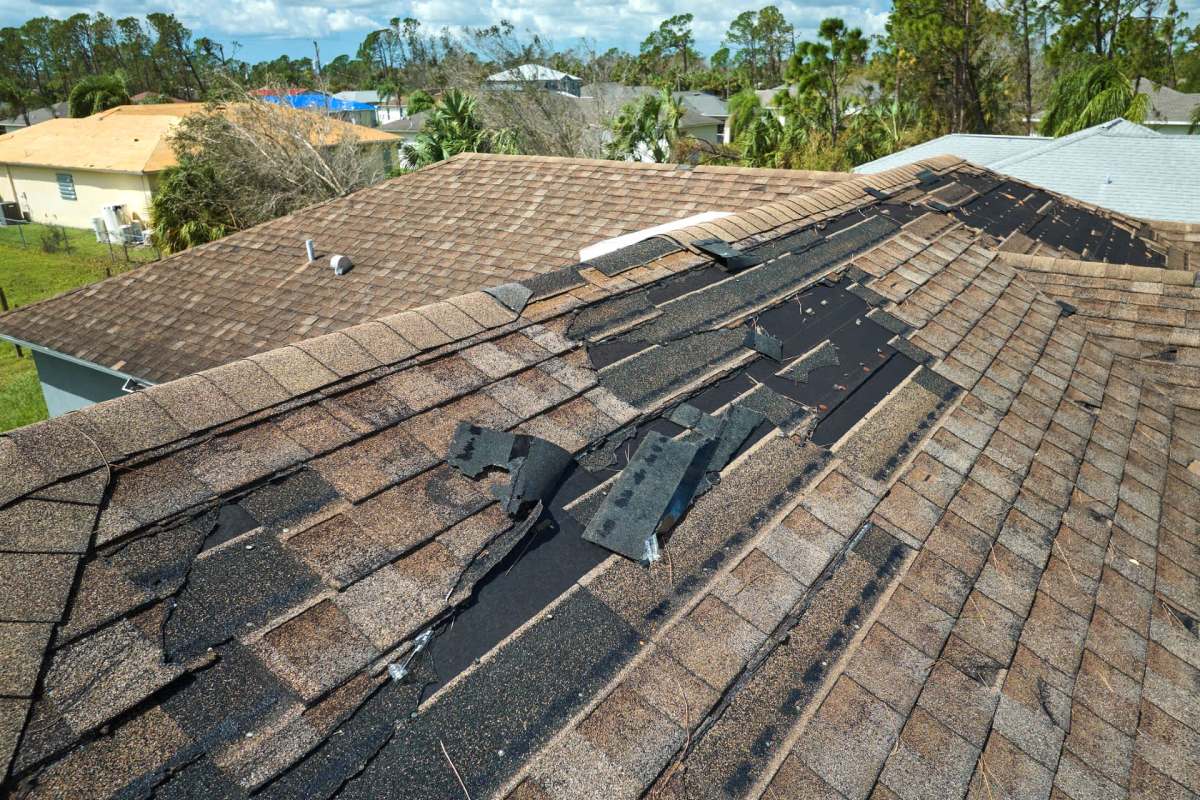
A couple hoping to buy their first home encountered a costly obstacle when their insurance broker said the property needed a new roof before they could secure coverage.
Here's what to know
In a Reddit post on the r/FirstTimeHomeBuyer community, the buyer asked for advice after the seller's proposed concession fell short of resolving an insurance issue that was preventing them from closing.
Inspections and a roofing company's assessment both called for a full roof replacement on the bank-owned property. The original poster said the house was built in 2002 and that, before inspections, the selling agent had warned that the roof was likely original and would have to be replaced.
"We were also told by our insurance broker that they will not insure the home until the roof is replaced, so we are at a roadblock for closing unless the roof is replaced," the original poster wrote.
The couple faced a $7,000 gap between the roofing estimate of $11,000 and the bank's $4,000 concession offer. That offer arrived a week after they submitted a repair addendum covering the roof and several other items.
More background
The couple offered the asking price because the bank was negotiating with another buyer, the original poster explained. Despite three months on the market before the couple's offer, the home had attracted only that one competing offer.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

The buyer reasoned that the bank would encounter the same insurance obstacle with another buyer relying on financing. Commenters, however, noted that the seller or bank might prefer to wait for someone willing and able to accept its terms rather than pay the full replacement cost.
Coverage that valued the roof at actual cash value allowed one commenter to buy a home despite its 22-year-old roof. They replaced it roughly two months into homeownership.
What can be done?
Several commenters advised using an independent insurance broker to compare coverage options from additional carriers. Another buyer replaced a 20-year-old roof with four layers of shingles during their first year of ownership, after securing insurance before the work.
A repair escrow could allow the buyers to replace the roof within an agreed period after closing, commenters said. They suggested asking the lender whether that arrangement was available.
One commenter had bought and repaired a bank-owned home with an FHA 203(k) renovation loan and recommended that the buyers explore the same program.
Others advised having the real estate agent show the bank both the $11,000 roofing estimate and the insurer's response to clarify why the purchase could not proceed.
Another commenter suggested having a roofing company chosen by both parties complete the work before closing. Under that proposal, the buyers would offer a higher purchase price in exchange for a larger credit, provided the appraisal supported it.
As it turned out, the original poster worked everything out.
"The seller/bank responded to our counter a little bit ago and agreed to replace the roof," they revealed. "We just received the signed repair addendum."
Where can I learn more?
Other buyers and sellers have also seen aging roofs put their deals at risk.
• A seller agreed to replace the roof, but commenters warned the buyer about potential warranty problems.
• A South Carolina VA buyer questioned a 15-year-old roof, then learned insurance could matter more.
• A homebuyer received an insurance quote, then learned an older roof threatened coverage.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.