

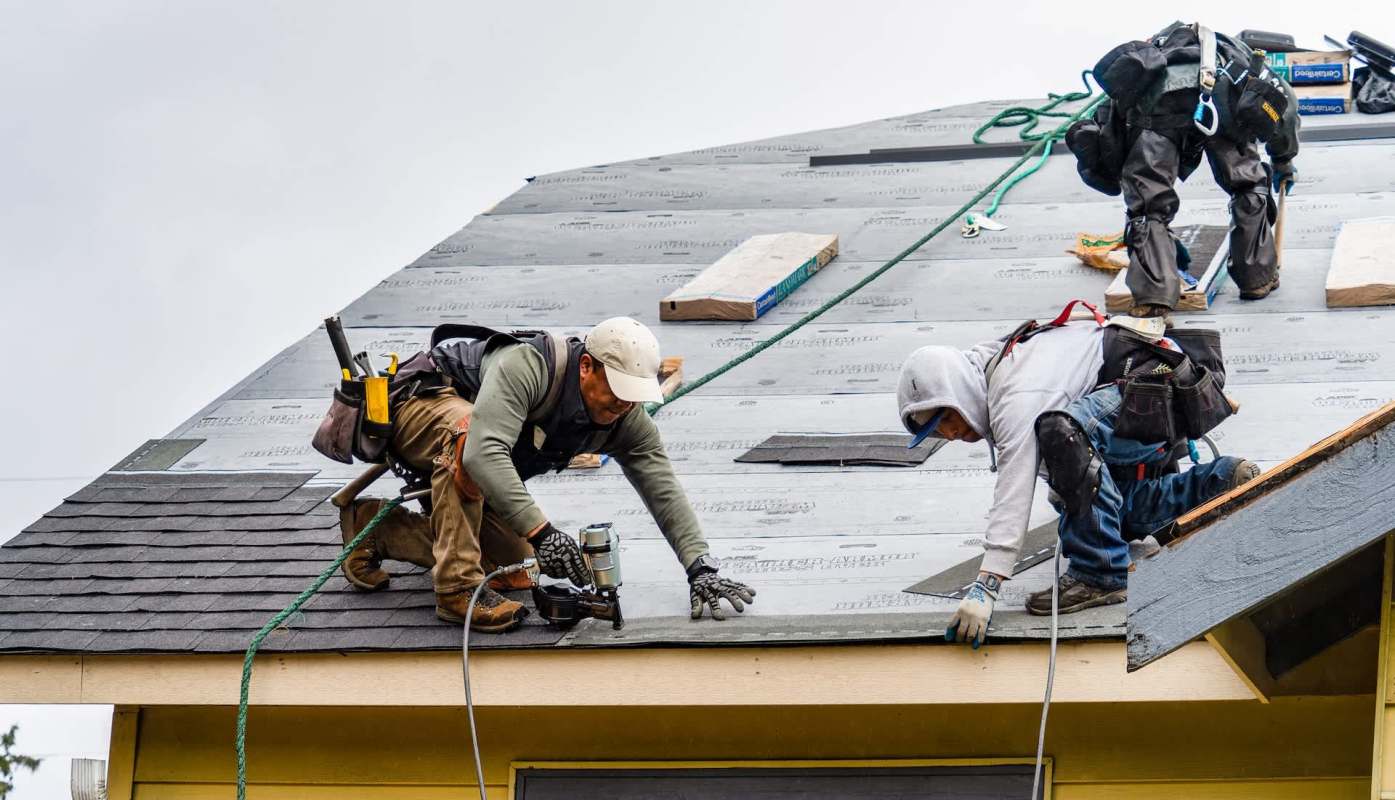
A Texas homeowner said a missing wind certificate on a 13-year-old roof sent their homeowners insurance premium to $5,300, and the remedy they were given was an $11,000 roof replacement.
With their budget already tight, they questioned whether replacing the roof was actually the only available option.
Here's what to know
In a Reddit thread, the homeowner said the insurer tied the increase to the missing certificate. They asked whether a full replacement was unavoidable. One reply cautioned against assuming the math would work out.
"Make sure they tell you what the premium would be with a new roof/wind certificate," they wrote. "The discount may not be worth it."
Another commenter said the original poster shouldn't try to squeeze out every last year of the aging roof anyway.
"Plan your savings to afford a full roof replacement every 15 years," they instructed. "Stretching a roof kicks the expenditure down the road but usually comes with higher cost due to water damage to the structural components of the roof."
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

More background
Several replies drew a distinction between a wind certificate and a roof warranty. One commenter called the certificate "evidence of fortification" and used their own home as an example, saying their roof carries a 140 mph rating and includes "six nails per shingle, instead of two," plus other build choices meant to improve storm resistance.
Another commenter suggested the insurer was probably asking for a "WPI-8 form."
The homeowner said they were navigating their first house without much guidance. They also said the cost pressure was severe enough that they were considering whether a 401(k) withdrawal might be the only way to pay for a new roof.
Another commenter shared a similar experience, saying their carrier threatened to not renew coverage unless they replaced an 11-year-old roof, and the job ultimately cost $12,000.
What can be done?
Before committing to a costly roof job, commenters repeatedly advised homeowners to ask the insurer to be specific. They said the homeowner should request, in writing, which document is needed and whether an inspection would meet that requirement.
If replacement becomes unavoidable, one commenter said the roof's wind rating should be written "in the contract," and the homeowner should confirm the insurer will accept the certificate that comes with it.
"Doing it without getting that cert is absolutely going to make it worse because you won't see the benefit," they added.
Other suggestions focused on shopping the policy more broadly. One commenter said an insurance broker could help because brokers "know who's looking for business."
A commenter who works in commercial insurance proposed another route: ask the lender what maximum wind/hail deductible is allowed, then talk to the agent about a percentage deductible and actual cash value treatment for the roof surface.
As it stood, the original poster was waiting on a new premium quote for a new roof and weighing all options after the insurer and an inspector got back to them.
Where can I learn more?
Homeowners are facing rising insurance pressure as extreme weather rears its ugly head.
• Across Texas, homeowners are facing soaring insurance costs as weather risks reshape premiums.
• On the Gulf Coast, a homeowner fought for hurricane-proof roofing approved despite HOA resistance.
• After a hurricane, one homeowner said insurance coverage fell far short of rebuilding needs.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.