

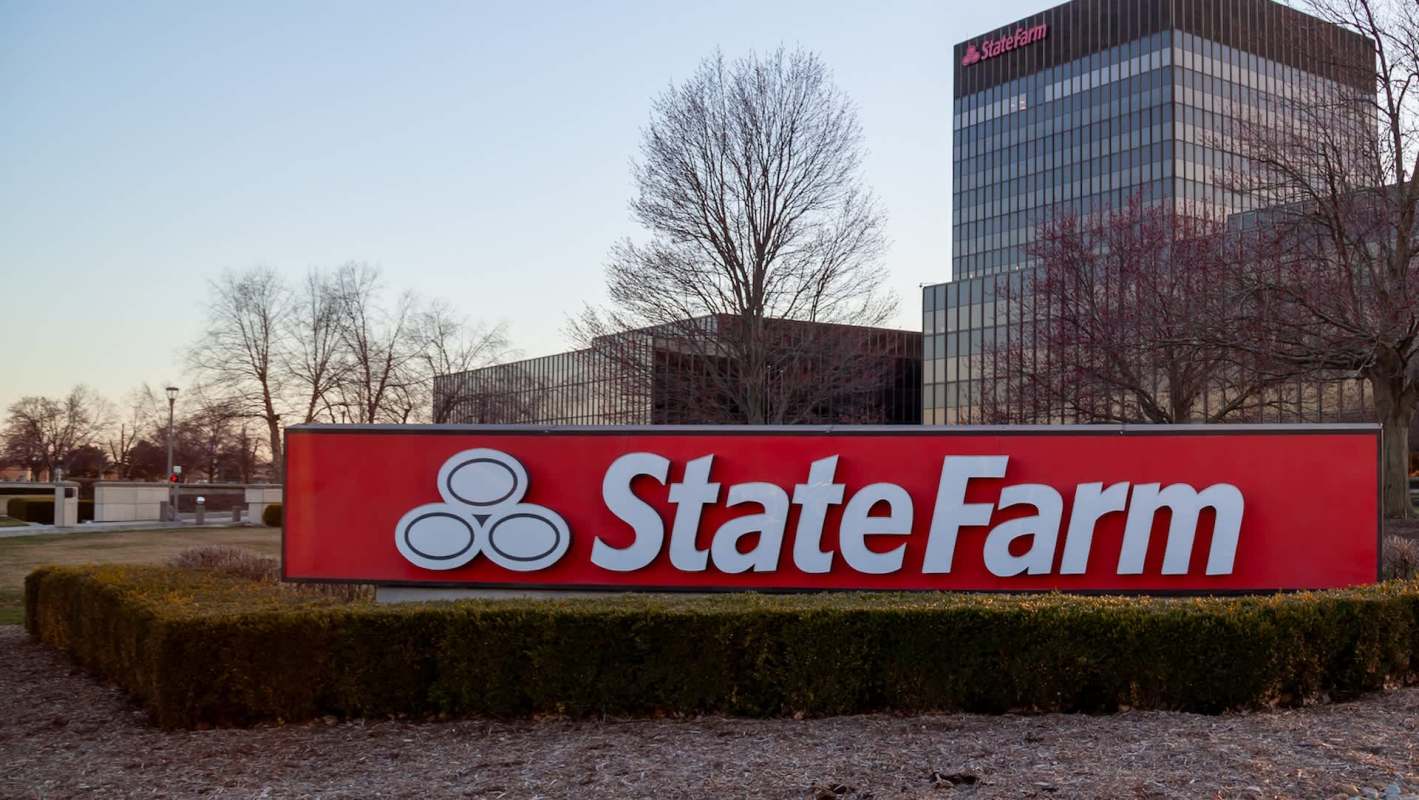
After a homeowner said State Farm rejected two hail-related roof claims, the insurer allegedly sent a warning letter flagging account "activity" and putting the policy at risk of cancellation. The complaint drew attention because neighboring houses had already replaced their roofs after the same storms.
Here's what to know
On Reddit's r/Insurance, the homeowner said they paid more than $40,000 in home insurance premiums over 30 years. Despite that, they received a letter warning that "activity" on the account left them "at risk for cancellation," even though they were paid nothing for a roof replacement.
According to the homeowner, the neighborhood saw two severe hail events, one of which involved a microburst. They said houses immediately around them all got replacement roofs, but State Farm inspections ended with their own claims being denied.
They also wrote that seeking a different insurer could backfire if new carriers see prior roof-claim requests and raise prices accordingly. The poster added that the roof was installed in 2013 and worried a future insurer might decide it had become too old to insure.
One commenter, describing a dispute with another carrier, wrote, "I somehow had the magic roof in the neighborhood they would not cover."
More background
Another commenter said a denied filing can still follow a homeowner for years, writing that "the claim is on your record now for 3-5 years" whether or not the insurer ever issues a payment.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

Others in the thread said the warning letter was not unusual. One called that kind of notice "an industry standard," while another pointed out that either side can choose not to continue once a policy term ends, a reality that can feel lopsided when a customer is dealing with storm damage.
The poster also noted that they had carried State Farm auto insurance since 1983. Several replies said that a long history with one insurer does little to protect customers when a claim becomes a dispute.
One commenter put that sentiment plainly: "It doesn't matter if you've been with them since the dawn of time. All that matters is the current policy."
What can be done?
The discussion focused less on waiting for renewal and more on contesting the denial now. One commenter wrote that "a public adjuster or an independent engineer's report could challenge the denial," and the homeowner should check the policy for an appraisal clause along with any deadline for reopening hail claims.
Another commenter shared their own experience after State Farm rejected a second roof claim tied to storm damage. They said they responded by asking for a return visit from an adjuster, a joint meeting with the roof inspector, and arbitration.
According to that commenter, the insurer's office then approved the claim after someone allegedly told them, "I knew this should have been paid out the first time you submitted." They later got a written warning about "excessive claims" even though one of the earlier claims had been denied and closed.
Where can I learn more?
These stories follow similar disputes involving State Farm and other homeowners dealing with denied claims, cancellations, and other coverage setbacks. They examine lawsuits, delayed payouts, and disputes over whether insurers handled home damage fairly.
• A homeowner accused State Farm of insufficient and unreasonable claims handling in court.
• Homeowners said State Farm dragged its feet on property claims after California wildfires.
• A California couple said State Farm canceled home coverage just before a wildfire destroyed their home.
• A frustrated homeowner said an insurer's months-long nightmare followed tornado damage and disputed repairs.
• In California, wildfire survivors faced painful new expenses after smoke damage repairs were denied.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.