

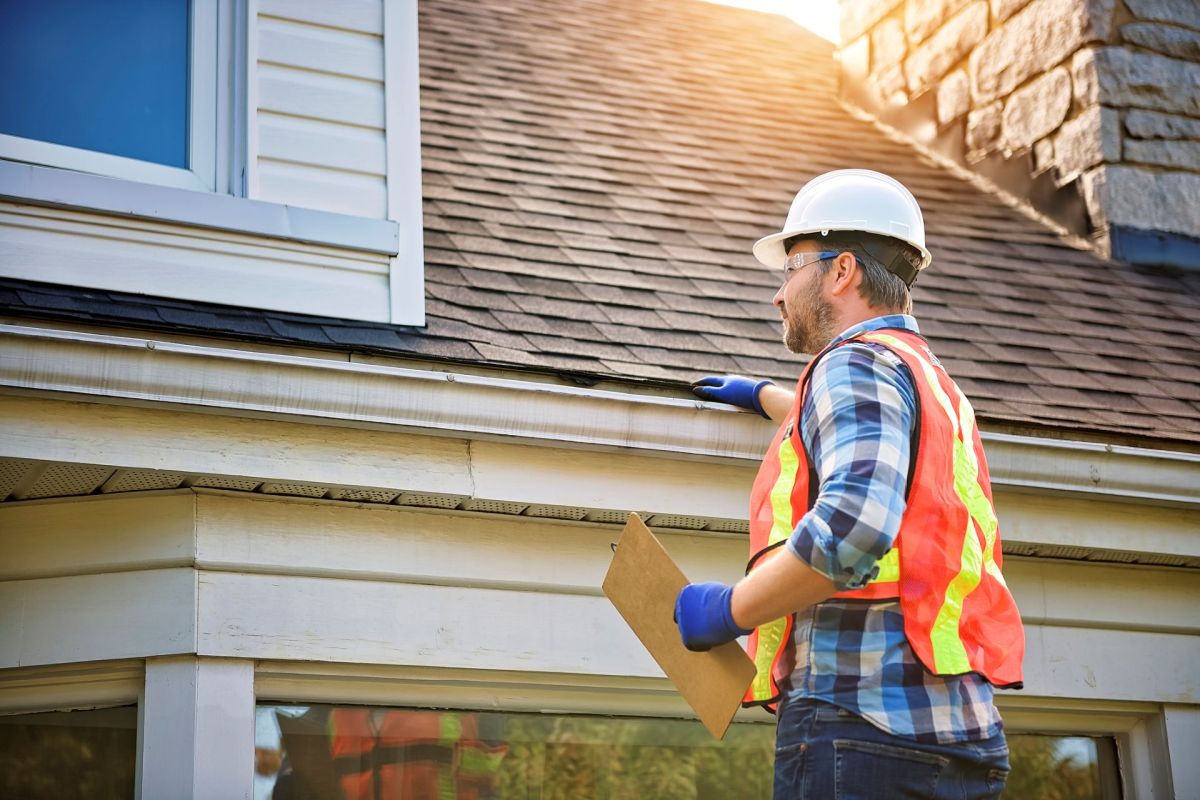
After buying a house, one homeowner discovered water damage in a corner of the property and received a repair estimate of $30,000 to $40,000, raising a new concern: whether turning to insurance might make things worse.
Their deductible was $10,000, and the roof's age had already made coverage harder to obtain, so the homeowner feared that submitting a claim could jeopardize the policy.
Here's what to know
In a post on Reddit's r/homeowners, the homeowner said the problem wasn't caught during the inspection and only showed up later in one corner of the house.
"Work estimate will be about 30-40k. Deductible is only 10k," the OP said.
They also explained that the home had an older roof, which had already made it difficult to find an insurer. Because of that, they worried a claim could lead the company to cancel the policy or demand a roof replacement before paying anything.
A common response from users was that the situation did not appear to involve a covered loss.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

One user said: "You need an event to have happened to make a claim. You don't know when the damage happened or what caused it."
Another user said, "Insurance will not pay for water damage that happened because of a leak/long term preexisting damage. They will likely (almost assuredly) not cover it and then drop you."
More background
The homeowner wasn't just dealing with a large, unexpected repair cost. The post also reflected a broader nightmare for buyers: uncovering damage after closing that may have been building for quite some time.
There was also concern about tackling the visible damage before fixing the cause, especially if water is still getting in. One user said they "would also hesitate fixing the water damage before getting a new roof, as the water intrusion may be related."
Cold weather added another complication. The OP said temperatures in their area made a roof replacement difficult, though another user said the job might still be doable outside a hard freeze or that a temporary solution could work.
What can be done?
Before committing to major repairs, users said the homeowner needed to identify the source of the problem. With one roofer already doubtful the roof was responsible, people in the thread urged further investigation into whether siding, flashing, foundation movement, or something else caused the damage.
The estimate's size also drew skepticism. One user described the $30,000 to $40,000 figure as potentially "outrageous" and advised getting "multiple quotes on the damage and roof" instead of relying on the first bid.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.