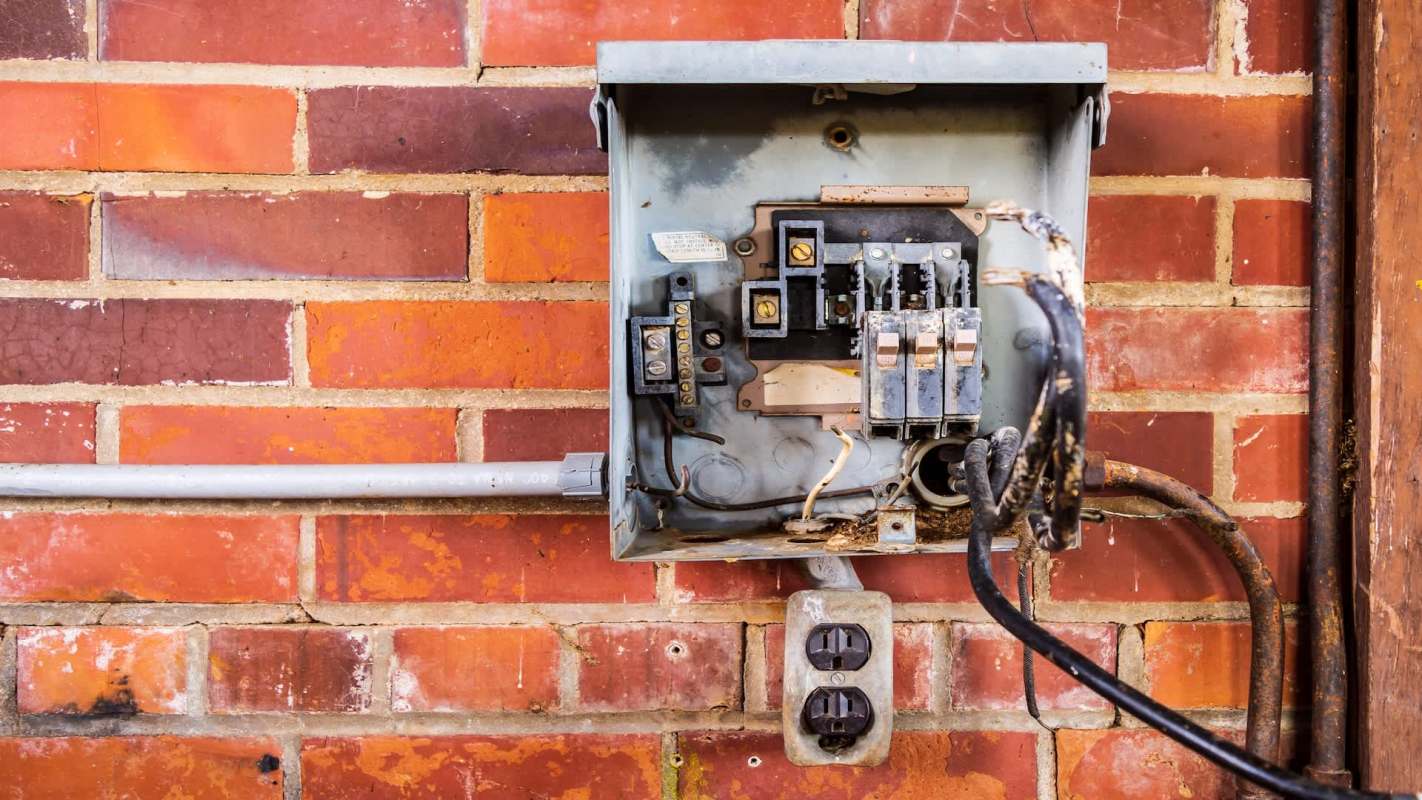
A first-time buyer said a favorable 6.375% mortgage lock was put at risk after a home inspection raised concerns about an aging electrical panel. The lender later said it would not fund the purchase until the panel was replaced.
Posting on the r/FirstTimeHomeBuyers Reddit forum, the original poster said the holdup could outlast the rate-lock deadline and leave them facing mortgage rates about one percentage point higher.
Here's what to know
The poster said the transaction became more difficult after an inspection identified the home's electrical panel as a brand associated with safety concerns from the 1970s or 1980s. They said the contract began on Aug. 28, and the original closing had been set for Sept. 16.
The plan later shifted to an escrow arrangement that would allow the electrical work to be completed after closing, pushing the date back to Sept. 23. Before that happened, they said the sellers waited until the original closing date to answer the repair request and then suggested using a cheaper electrician even though permits could take as long as six weeks.
The situation changed again on Sept. 22, when the buyer said the lender informed them that underwriting would not release funds unless the panel was replaced first. The whole thing amounted to a "nightmare experience."
The original poster added: "I am losing my lock and rates are now a whole percentage higher (7.375). What should I do? Walk away?"
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

A highly upvoted comment suggested the OP's instincts were correct and their leverage could pay dividends: "Yes, walk away. I suspect when you do they will quickly find a solution."
More background
The poster also said they had agreed to pay $5,000 over asking after the sellers initially sought $10,000 above the list price. They chalked that up to really liking the place and said it was a compromise.
One commenter warned that "extending your lock is likely far cheaper than finding a new lender and getting a fresh market rate…and that new lender is unlikely to do an escrow holdback for repairs either, those are fairly uncommon and difficult to get with most lenders."
Still, commenters were wary of the whole situation.
"Buying a house should be as close to a drug deal as possible - if anything seems off -> walk away," one advised.
What can be done?
The consensus in the thread was that the original poster shouldn't put up with the seller's poor treatment.
By threatening to walk away, they could push the sellers to do right by what they agreed to. Commenters also wanted them to extend the rate lock and hold onto the favorable number.
"This is the best advice," one commenter said of walking away. "The sellers made this difficult for you and they didn't have to. Tell them it needs to close before the 28th or you walk."
Where can I learn more?
Other homebuyers have run into deal-threatening surprises, from solar leases and long-term contracts to unexpected fees.
• A first-time buyer was stunned when a surprise solar lease appeared in the seller's paperwork.
• A seller nearly derailed a sale over an undisclosed $12,000 fee on solar panels.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.