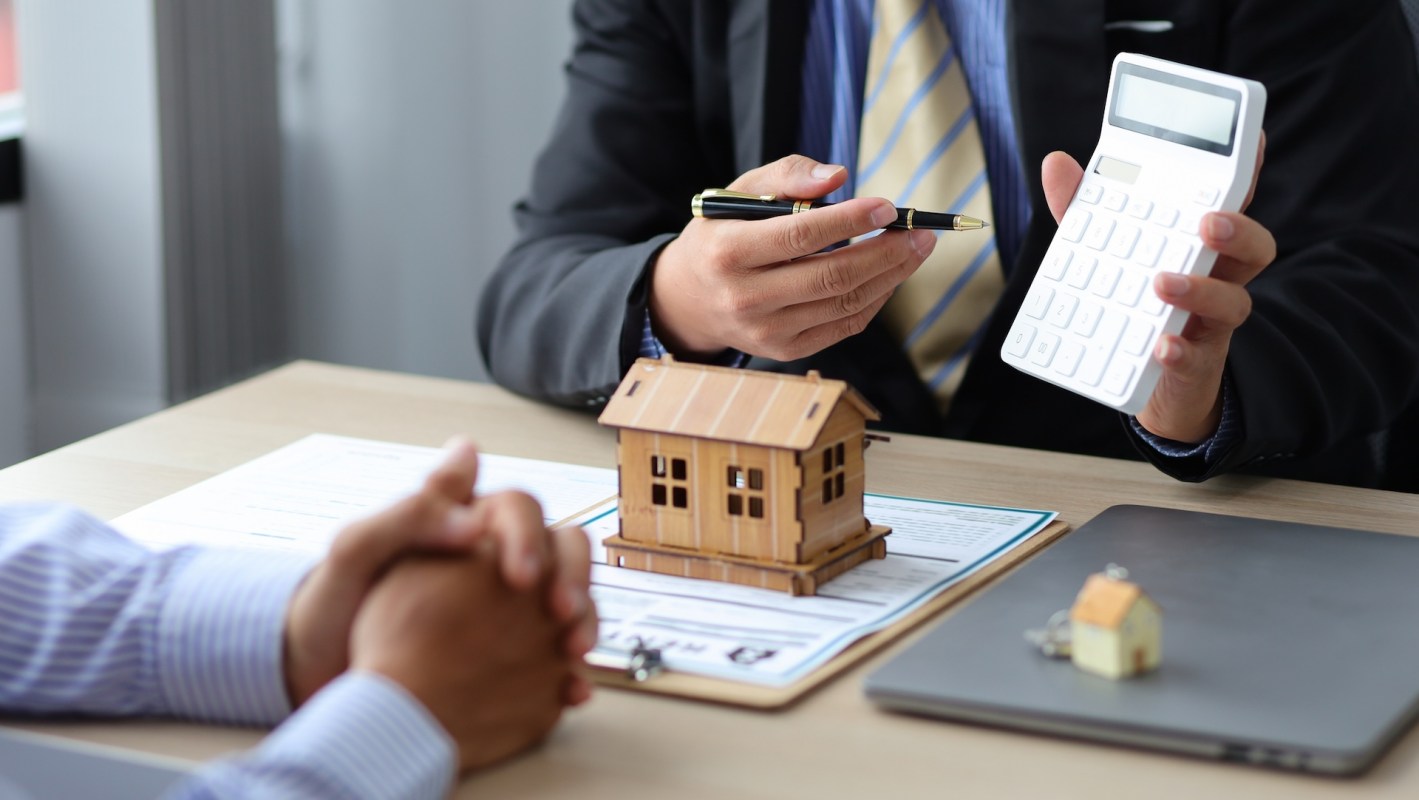
A high income does not automatically make a big mortgage feel safe, especially when a large share of earnings comes in unevenly.
That was the dilemma for one Michigan homebuyer trying to decide whether a $4,800 monthly housing payment on a $725,000 home would still feel manageable in weak years.
Here's what to know
The buyer told Reddit's r/Mortgages community that their household income varied widely, from about $260,000 in some years to over $400,000 in better ones. This original poster then asked the subreddit for a "gut check" on buying a $725,000 home in Oakland County with 15% down ($108,750) and a $616,000 30-year fixed mortgage.
"Would love to hear your experiences, thoughts, or things you wish you knew before taking on this price bracket!" the OP wrote.
The OP said their household had minimal recurring debt, with about $800 a month going toward two car leases. They also expected to sell their home and use about $85,000 from that sale toward the down payment.
Many people urged the buyer to judge the purchase against the household's lower earning scenario, not its best years. "First thought is to make the judgement based only on base salaries, not bonuses. You can get in deep trouble counting on a bonus that doesn't appear," one commenter wrote.
TCD Picks » Quince Spotlight
💡These best-sellers from Quince deliver affordable, sustainable luxury for all

Users said the listed payments could work but only under the right circumstances. "We make $240k combined, our [principal, interest, taxes, and insurance] is $5,800. No debt. We max out retirement, have two kids, and we are doing just fine," one said, while another offered a more cautious point, writing: "How much of an emergency fund do you have? If either of you is out of work for any period of time, you won't be able to afford the house long."
Another theme was how much cash to keep available after closing. Reaching 20% down would remove private mortgage insurance, but commenters noted that holding onto liquidity can matter just as much if early repairs and surprise expenses show up.
What can be done?
For buyers with fluctuating incomes, running the numbers using a floor rather than a ceiling can show whether a mortgage will still work. If it does, a strong year can act as a cushion instead of a necessity.
It can also help to decide ahead of time how much liquidity should remain untouched after closing. That includes emergency savings, moving costs, maintenance reserves, and any known near-term expenses such as childcare or vehicle replacement.
In some cases, a low down payment paired with a big cash reserve may be safer than draining savings just to avoid PMI. Some commenters suggested viewing PMI as a temporary expense rather than a deal-breaker. As one put it: "[PMI] is not the end of the world. I had PMI on my first home. I did make extra payments to get to the magic 20% as quickly as possible."
Where can I learn more?
The costs in this kind of decision can stretch well beyond a mortgage payment itself. These stories look at nationwide affordability, rising insurance costs, and the risks buyers are weighing.
• A Harvard analysis found median homes now require about $120,000 in income.
• Across the U.S., high home insurance rates are increasingly freezing out would-be buyers.
• Zillow found over 80% of buyers now weigh property-tax and climate risks before bidding.

Get TCD's free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.